Liberalism and Its Discontents – Francis Fukuyama 2022

US politics are very polarized. Left and Democrat are nearly synonymous. Right and Republican are nearly synonymous. Professor Fukuyama sees an even greater threat from the challenges of the “New Left” and the “Hard Right” to the core principles of the “classical liberal” political system of the United States.

The book is a defense of “classical liberalism”. Limited government power. Legal institutions protect individual rights.

Not US center-left political liberals or EU center-right political liberals.

Classical liberalism is under attack from right – nationalist, cultural, authoritarian and from the left – postmodern theory, inequality, identity politics, group rights.

Classical liberalism born of history, 1700-1800, rationalism, science of enlightenment, anti-conservative aristocracy, church, tradition, favored groups. Partial solution to the post-Reformation religious wars. Dominant world view 1945-1990 as communism and fascism lost war of ideas. But, also opposed by romantic movement 1800’s, nationalism late 1800’s, communism 1900, fundamentalist religion, etc.

Inherently a practical solution to a world with unavoidable diversity of opinion and interests: religious, ethnic, state, culture, race, gender, class, etc. Privileges individual over community. Privileges institutions (law, military) over individual political actors. Privileges pragmatism over theoretical cleanliness. Privileges conflict avoidance above utopian justice. Privileges incremental change to revolution. Privileges all individuals’ rights versus just the most valuable individuals’ rights.

In a more diverse, global world, “classical liberalism” remains a solid choice for organizing society. The burden for promoting change lies with the critics.

1. What Is Classical Liberalism?

A. Individualist. Claims and rights of individual get priority over claims of any group.

B. Egalitarian. All individuals have an equal legal and moral standing in society. This contrasts with systems and philosophies where groups are more important. Nations, monarchies, aristocracies, oligarchies, autocracies, religion, class, race, etc.

C. Universalist. Humanity as a species is first. Specific historical forms, institutions, groups, leaders, cultures, etc. are secondary.

D. Meliorist. Social and political institutions and arrangements are imperfect, subject to improvement or decay. Liberalism is inherently pragmatic, accepting that no system or policy will meet the needs or reflect the values of all citizens. Compromise and tolerance are required to govern a state with unreconcilable differences. Liberalism sought to end the “wars of religion” where opposing sides were certain they were right and willing to fight. Liberalism accepts the need for a “strong state” to militarily offset the powers of “strong men” or “strong groups”, echoing Thomas Hobbes.

Individuals have rights because they are human. These rights are more important than social, political, economic and cultural institutions. Freedom of speech, association, belief and politics. Right to own private property and transact by choice. The right to vote and influence political decisions were added through time. Starting with these principles, governments are freely formed by individuals (contract theory) in order to protect individuals and preserve these rights.

Critically, “liberalism” is based on ideas, rational philosophical ideas, rather than history, tradition or power, per se. It is not only based on ideas, but also on history and experience. The “rational” dimension of “liberalism” can cause proponents and defenders to take positions that are considered “extreme” by others.

Contrast “liberalism” with “democracy” which is “rule by the people”. Democracies provide voting rights to most citizens and limit the power of strong groups to restrict the vote of the people. Not all liberal states are democracies. Democracy has expanded greatly during the 20th century. “Liberalism” provides an infrastructure that supports democracies and buffers attacks on them.

The emphasis on individual rights in “liberalism” causes an emphasis on laws and the rule of law, independent of the exercise of direct political power. The history of powerful rulers disregarding any inconvenient “rights” made the early proponents and adopters of “liberalism” champions of this “checks and balances” approach to governance. Again, critics of “liberalism” point out that highlighting just legal rights can lead to unbalanced political systems and societies that downplay other values and interests.

“Liberalism” claims to be a moral system. It honors human dignity, autonomy and choice. Individual choice is supported in most areas of life, constrained only by legal and regulatory limits agreed upon by political representatives. This right to choose applies to all people.

Economic benefits stem from property rights, freedom to transaction, legal institutions and the “rule of law”. Individuals invest in potentially profitable opportunities because they are confident that they will be able to capture and maintain most of the benefits from successful ventures. Historically, this has delivered strong economic growth with positive spillover benefits. Some critics question the use of economic measures such as GDP and growth as proxies for society, but the “order of magnitude” growth levels under “liberal” economic systems clearly provide enough benefits to allow society to prosper and redistribute as desired. Liberals also tend to support “free trade” policies for the movement of goods, services, finances and people because these voluntary trades result in net added benefits to both sides.

“Liberalism” is strongly associated with the “enlightenment” and the “scientific revolution”, relying upon logic and evidence to make objective decisions. It is also linked with the “scientific method”, noting that the free marketplace of ideas is effective in evaluating competing claims and drawing conclusions, even if those conclusions are only formally probablistic, rather than certain.

Liberalism emphasizes tolerance and compromise as virtues in order to defuse strongly held differences of opinion. Hence, it is inherently in conflict with any religious or political view or system that believes that it holds the only “truth” and that this “truth” must be consistently reflected in political, regulatory, judicial and social decisions. This tolerance for differences aligns liberalism with ecumenical religious groups and “relativist” ethical philosophies. It also aligns liberalism with a more dovish foreign policy approach recognizing the “rights” of all states and the global community as valid. Because of its tolerance for diverse religious views, liberal secular states are sometimes seen as opposing religion or supporting atheist or agnostic religious positions.

Historically, liberal states have resorted to war to protect what they saw as essential national interests.

Liberal states focus on the philosophical principles that shape nation-states (freedoms, rights, liberties) rather than religious, ethnic or cultural dimensions (blood and soil).

Equal rights for all people was slow to develop in liberal states, even when the principles were enshrined in declarations, constitutions and bills of rights. On the other hand, the ideals of equality played a role in expanding equality through time.

Historically, the new “liberal” systems were supported by groups opposed to the existing, “conservative” powers: monarchy, state churches, aristicracy, landed gentry. Capitalists, property holders, traders, urbanites and professionals supported “liberal” systems which provided them with greater economic, political and social rights than the received systems. Through time, the more ancient powers lost influence and the new “middle class” accumulated power and influence in the “liberal” system.

“Liberals” celebrated the defeat of fascism and Nazism after WWII and the defeat of Soviet communism in 1990. Fukuyama’s 1992 book “The End of History and the Last Man” documented this achievement. The widespread adoption of basic liberal principles and “mixed capitalist” states was a clear economic success and no clear competitor remained in 1992.

Left- and right-wing political groups emphasize different parts of autonomy or free choice in the “liberal” state. Conservatives and neoliberals (Reagan, Thatcher, free marketers) emphasize free economic choices and a corresponding limit to government economic roles. Democrats, leftists and progressives emphasize personal social autonomy. Libertarians emphasize all freedoms and oppose large government roles of any kind.

2. From Liberalism to Neoliberalism

The post-WWII “good times” rolled for 3 decades, but the growth of government activities, slower economic growth, stagflation, international crises and growing political opposition to the “status quo” lead to a reaction against the general economic and political consensus that a “mixed economy” was “good enough”. Reagan and Thatcher won solid election victories with clear messages of “less government”.

This pro-business, anti-government philosophy became known as neoliberalism and was broadly adopted in many western countries, with left-leaning parties adapting with more pro-business policies and less government activism (Clinton).

Fukuyama points to inefficient, ineffective and overreaching government as drivers of this major change in political views. He notes that reduced regulations, outsourcing, divestiture and lower taxes did lead to more competitive industries and economies leading to increased growth and employment.

He also paints neoliberalism as an extreme view, discounting any role for government and unduly emphasizing just the economic dimension of public policy. He doesn’t see a close tie between “classical liberal” political states and neoliberal political philosophy and tactics. Like most “liberals” and economists, he sees various roles for the government in a modern state due to inherent “market failures”. Basic consumer and environmental regulations, military and public safety, anti-trust, financial market regulation, public goods (education, infrastructure), regulated natural monopolies, limits to inequality. He suggests that public policy should focus on the effectiveness of government services first and the share of government services second, without and demonization of government or lionizing of “free enterprise”. He notes that the share of government services provided is a political choice made within a “liberal” system that could be very low (20%) or very high (80%).

Fukuyama outlines the basic economic argument for “free trade” (opportunity to make both parties and societies better off) and notes that this is of little succor to those who lose from free trade (workers, businesses, localities), especially when policies and programs to help them recover are non-existent, underfunded or ineffective.

He observes that the political failures to ensure efficient governments, effective politics (vetocracy), limits to inequality, proper financial regulation and balanced trade have driven opposition to government, politicians and political parties on the left and the right from critics on the left and the right!

3. The Selfish Individual

The author sees neoliberalism and its libertarian cousin as distortions of “liberalism”, focusing solely on an extreme view of individual economic results alone.

Property rights matter, but no more than other rights of choice. Property rights are supported by government institutions, so the quality of government matters. The original distribution of property is an important factor which cannot be “assumed away”. There is no reason to prioritize financial rights or physical property rights over intangible property rights or other things which humans value. Economic efficiency and growth are valuable, but tradeoffs exist with other socially valuable goals: peace, security, opportunity, expression, speech, association, equality, fairness, solidarity, growth, etc.

Consumption is not the highest priority. Production matters, not supply-side economics, but human connection to producing. Pride of authorship.

Anti-trust regulation is required to offset monopoly power. Political action is needed to offset regulatory capture.

Libertarian approved theory of “spontaneous order” has little historical or theoretical support. Markets, common law and social Darwinism are not simply “facts”.

The state also has a role in international trade policy, industrial policy, R&D, defense, public goods airports, etc. Not either/or.

The economics discipline’s reliance on selfish utility maximizing agents is not supported by casual observation or behavioral economics. People use crutches to make decisions. They work from habit. They are OK with “good enough”. Individuals value social goods like friends, status, respect, pride, safety and power. They consider “fairness” and other principles. Choices are influenced by social norms.

People play various roles in groups. The simple rational model of principal-agent is inadequate to explain behavior. People follow leaders, norms and procedures. They discriminate based upon prejudices even when it is economically irrational. People belong to many groups which influence their behavior: nation, class, religion, family, neighborhood, profession, gender, gender preference, age, marital status, civic, artistic, political, social, athletics, etc. The materialist, determinist, rationalist, objective, calculating model of human behavior is clearly inadequate.

4. The Sovereign Self

The individual, good inner self evolves to become a self-worshipping god.

When the “liberal” model first evolved, a Christian (or at least deist) religious framework existed in most societies which provided a moral basis for politics and society. Freedom of choice was made within a largely fixed moral framework for most citizens. Through time, the individual grew relative to the community and individuals were then positioned to choose their own moral framework. This positioned individual autonomy to be the supreme virtue, above all others.

Autonomy evolved from individual choice to group choice and rights. This resulted in questions about the underlying basis of “liberalism”: individual versus group, universal human rights or differences, and the requirement of tolerance.

Martin Luther’s focus on “salvation by grace alone” focused on the individual, especially the internal individual’s thoughts in contrast with the mediation of salvation through the authority of the church and priests and the works of man. Jean-Jacques Rousseau’s vision of uncivilized man as inherently good further focused attention on the individual, since it was possible to shape this blank slate which could be perfected, in contrast with the doctrine of “original sin”. Immanuel Kant used reason to define the limits of reason and to develop a rational basis for morality, essentially the golden rule, optionally expressed in the maxim that man should always be an “end”, but never just a “means”. Again, the individual was highlighted and separated from religion. In this context, the ability of each man to reason and make choices was elevated as a supreme virtue, potentially above morality itself.

Fukuyama indicates that the basis for extreme individualism was available from the start, but only in the 20th century, after two world wars, Darwin, Freud, Marx and Hitler, was this variety able to blossom. He stresses the growth of the self-help movement as a key accompaniment to the philosophical, political and academic evolution. Therapists replaced priests and ministers as the guides for personal growth.

The author focuses on the philosophy of John Rawls in his 1971 “Theory of Justice”. Rawls provides a theoretical framework of choosing society’s rules in a “veil of ignorance”, where each individual does not know what his or her abilities, talents, wealth and opportunities will be. Rawls argues that a “rational man” in this situation would set rules that would protect him from the worst-case circumstances, even if that required transfers of resources and limits to opportunity and overall output. This matches the rational “mini-max” principle developed in post-WWII game theory. This provided American political liberals with a justification for their preference to reduce inequalities of income and wealth through government redistribution.

Fukuyama argues that Rawls goes “too far” in removing any moral basis from society. This “moral” choice is made almost mechanically on the basis of thought alone. The political influence of real individuals is ignored. “Justice” is defined without reference to “the good”. Rawls says that the human subject is separate from his attributes (wealth, status, character, genes) which are assigned arbitrarily. Hence, all property belongs to the state and can be redistributed as required.

Robert Nozick’s 1975 book “Anarchy, State and Utopia” challenges this view, arguing that individual rights cannot so easily be acquired by the state based upon a philosopher’s story. Resurgent libertarians argue that the individual owns all property before the state has any rights. Philosophers since that time have been busy contrasting the “individualist” and “communitarian” views of ethics ever since. Even left-leaning philosophers like Michael Sandel criticize this “thin moral world” of choices without communities, traditions or other moral values. Fukuyama says that this most modern view of ethics compared with historical ethics is parallel to the evolution of liberalism to neoliberalism. A valid principle has been elevated to an absolute standing and lost its rationale and practical effectiveness.

Fukuyama claims that Rawls’ provides a philosophical basis for moral choice that is solely individual, independent of society. He notes that many commentators on “liberal” political systems see a requirement for some level of shared moral belief, including tolerance and public-spiritedness. The growth of the self-help movement, personal growth and self-actualization in the postwar era provided practical experience of the self, detached from religious and social norms. Rawls’ philosophy said that is “fine”. Existentialist philosophy evolved into postmodernism and complemented Rawls’ political and ethical philosophy. Fukuyama argues that these views undercut the social basis required for a liberal political system and that individuals lured into believing that total personal autonomy is possible will be dismayed when they learn this is not so and thereby reject historical individual based political views and pursue group-based views (next chapter).

5. Liberalism Turns on Itself

In the next two chapters the author outlines how modern “new left” thinkers have created a political theory that is quite opposed to “classical liberalism”, especially as outlined by John Rawls. “Critical theories” and postmodern philosophy reject any strong individualistic philosophy that does not give strong weight to groups, communities and society. Ironically, in this debate, classic conservatives and “new left” progressives are aligned, raising up the group as a critical basis for ethics, morality and a just political state.

Fukuyama focuses on the nature of the individual self in Rawls’ philosophy compared with that of others who propose “critical theories”. While most citizens don’t really want to dig this deep, Fukuyama and other philosophically minded academics, critics and political leaders consider this essential. In the Rawls model, and in other “classic liberal” models, the focus is on the rational individual facing a world of choices. From this existential situation, the need and desire for certain rights and freedoms to support these choices by the “choosing being” are developed and a consistent political and ethical model is developed. As with the ultra-skeptical Rene Descartes, the mathematical Newton and the medieval philosopher of science Occam, “less is presumed to be more” in “classical liberal” philosophies. If a few assumptions and observations about individuals are sufficient to create a robust and effective model, why make reference to groups or specific moral goods, especially after many philosophers wrestled with the distinction between facts and values, is and ought, descriptive and evaluative claims and concluded that these two groups of ideas simply don’t exist in ways that they can be combined and evaluated. In practical politics, liberals of all stripes are ready to insert and advocate for their “progressive” values, including the importance of groups and specific moral values. But this is missing from the philosophical model.

Philosophers have long seen individual identity as a crucial aspect of being a person, especially as a choice making agent. Without self-awareness and a personal identity, how can one make choices? For “liberals” the choosing agent makes choices which build that identity, preferences and moral framework to guide choices. Per Rousseau, the individual starts with a “blank slate” and constructs this identity. The individual is first; the environment, including family, groups and society is secondary.

For “critical theorists”, some group characteristics that are imposed upon the individual (race, ethnicity, gender, gender preference, culture) are much more fundamental. The individual may begin with a “blank slate”, but society forces its perceptions and values regarding these group characteristics upon the individual no matter how hard he or she may try to choose for him- or herself. The critical role of society, the group, the system, the power structure is unavoidable.

To the common man, even a very interested “John Q Public”, this seems to be “much ado about nothing”, senseless quarreling over “nature versus nurture” or “which came first, the chicken or the egg?”. But for philosophers, academics, theorists and advocates, getting to the “root cause” is precisely the most important topic.

“Identity politics” is aligned with the view that an individual’s identity based on these key groups is essential. Those with power in any society use that power to create ideologies, structures and norms that define these group identities in ways that benefit the elites of that society. Hence, individuals in the non-preferred categories are unwittingly deprived of their rightful power and marginalized. Individuals shaped and governed by society’s messages, institutions, laws, thoughts and actions must be re-educated to understand the “real” situation and combat their exploitation. This sounds very much like the Marxist view of western society before communism was discredited by the real-world actions and results of the Soviet Union. The marginalized groups replace the marginalized workers, both needing to be enlightened by the few who have “true insight”.

From the 1960’s “New Left” forward, proponents of “critical theories” and “identity politics” have rejected “classic liberalism” as being an ideology of the powerful classes designed to maintain power and exploit the “masses”. The progressive left rejects individualism alone as a valid basis for any meaningful political philosophy. It observes little progress on reducing inequality or helping individuals to develop their true identities free from socially imposed masks. Unconstrained capitalism is linked to “classical liberalism” and found guilty of supporting the elites and oppressing the marginalized groups. The divide between the center-left and far-left is very deep.

In 1964 Herbert Marcuse outlined the basics of this transition from Marxist to “new left” political thought in “One Dimensional Man”. So-called liberal democracies did not promote equality or autonomy. The elites captured the corporations and legislatures and controlled society to maintain political, economic and social control by the elites. Charles Reich’s 1971 The Greening of America provided a more digestible best-seller with a similar message. “Free speech” was deemed a tool of the powerful and questioned. The “working class” was determined to be coopted in a consumer society where Vance Packard’s “hidden persuaders” forced them to consume ever more, work ever more and envy others. Individuals didn’t really choose; they only had the illusion of choice.

The New Left questioned the individualistic “contract theory” underlying “classic liberalism’s” political model, highlighting examples of slavery, worker and marriage contracts that were clearly imposed rather than negotiated. They argued that the exploitation of society by capitalists, dominance of neoliberal ideology and capture of regulatory agencies were inevitable. They outlined the long history of colonialism, imperialism, destruction of natives and presumption of a superior “western civilization” as evidence that the powerful groups would always do whatever is required to maintain control. They documented the ways in which political “checks and balances” provided the ruling elites with additional levers of power. They concluded that “classical liberalism” was intellectually and historically bankrupt.

Fukuyama presents some counterevidence to oppose these claims. Liberalism does not exclude groups, morals, society or other values. Real-world liberal political systems incorporate these values. An extreme form of liberal philosophy (Rawls) is just a straw-man, not representative of how actual liberal political systems work. Liberal states have made social progress through time, voluntarily investing more individuals and groups with greater rights. Economic progress is obvious. Liberal states invest heavily in social welfare programs. Liberal political states make it possible for progressives, liberals, conservatives and hard right groups to all have voice and political influence. International trade and economic growth make possible individual choices, health, art, safety, security and self-actualization. The individual focus of the liberal state frees individuals from the constraints of traditional family, kin and religious bonds. Meritocracy is consistent with a wide range of human development and actualization ideals. Migration continues to flow from states with limited individual rights to those with liberal rights, the rule of law and economic advantages. Liberal states support multicultural societies. The worst “sins” of “western civilization” and liberal states, including colonialism, are receding into history. Eastern European, East Asian and other states have successfully adopted the liberal state model. “Checks and balances” result in sustainable political changes and prevent authoritarian rule.

6. The Critique of Rationality

“Classical liberalism” is also closely associated with a rational approach to determining truth. Historically, logically and currently it uses and supports the “scientific method”. An objective reality exists and can be discovered by observation. Theories begin with self-evident assumptions and are fleshed out using logic. Theories are evaluated by the testing of predictions. Theories build credence as they develop more testable hypotheses which are validated or not invalidated. Humans can understand this objective reality and use science and technology to control nature. Scientists keep facts and values separated. Scientific conclusions (theories) are inherently probabilistic, but relative confidence can be determined and agreed upon. Techniques to verify propositions are agreed upon by professional scientists. Evidence is more highly regarded than individual assertions. Testing is defined so that it can be repeated and verified. Progress accumulates, although changes in scientific theories do occur. Science, like the courts, journalism and the military, is led by professionals who are largely independent of political power.

“Critical theory” proponents treat science and rational discourse as another social institution subject to control by the powerful elite.

In 1882 Friedrich Nietzche proclaimed “God is dead”. The decline in religious belief and influence in western Europe, especially in elite circles, allowed this to be stated and analyzed. Nietzche was saying that society had substitutes for the concept of God as a way to explain the world and manage suffering, so God was no longer necessary. He saw that Christian morality underpinned western society and politics and that the loss of this framework was a radical and threatening change. In such a world without shared morality, the only virtue or value was power. Nietzche outlined the contrasting lives of those living by the Christian “slave morality” and those of a noble superman who sees himself as the measure of all things. He concluded that “there are no facts, only interpretations”. Nietzsche did not convince many of his views then or now, but he opened the door to considering such different viewpoints. No morality. Only power. No objectivity.

Nietzche was a precursor to the philosophical approaches that lead to postmodernism. Nietzsche’s professional training was in philology, the study of a language’s grammar, history and literary tradition. His contemporary, Ferdinand Saussure, was a pioneer in the development of linguistics as the science of language. He separated words from a direct link to reality. For him, the human process of speaking is dynamic and the meaning of words are shaped by the speaker, disrupting the naive view that words simply signify things. The act of speaking also shapes the worldview of the speaker, making language a subjective entity.

Saussare’s subjective approach to language and meaning lead a series of French intellectuals including Jacques Derrida in the 1960’s and 1970’s to develop an extension of this view. The claimed that the external world is actually created by the words that we use to describe it. Other philosophers had considered what was “really real” previously and some had proposed that reality is really a subjective creation of the mind rather than an objective, material fact but this approach had limited impact outside of philosophy. As philosophers focused on language as a primary topic during the twentieth century, this idea became more attractive and, in some sense, “plausible”. The next step was to link language back to the power structures which determine language. Now, we have the power structure determining language which determines thought which creates reality. With this “structure”, a critic could “deconstruct” the underlying meaning of any important writings and show how the power structure guided the writer to reinforce the beliefs and interests of the power structure. Many doctoral dissertations could be written to show that all of “the western canon” was comprised of individuals unwittingly working for the power structure.

Michel Foucault expanded from this criticism of the true meaning of written language to a broader attack on all modes of thinking done within the framework of language guided by the “powers that be”. A subject like cross-cultural studies was inherently defective due to assumptions shared by the ruling western culture. The liberal idea that all individuals share an underlying moral core was rejected by Foucalt and the postmodernists. Instead, the shared lived experience of group identity is considered most important and differs from person to person. A privileged white American male simply cannot understand the experience of a marginalized non-white non-American female. The group experience is most important. The combination of various dimensions results in the concept of intersectionality which defines the most relevant group in even finer terms. By denying the ruling group member’s ability to understand the experience of the minority group member, this approach undercuts any authority of the ruling group member.

Fukuyama says that some of these insights about the role of language, subjectivity, tools of power, self-deception, alignment of interests, hidden biases, unconscious prejudices, etc. are valid in some historical situations. However, he does not agree with the philosophical or political conclusions that have been drawn. He notes that the deconstructionists and postmodernists have written in ways to make their theories difficult to describe or evaluate. He asserts that the extremely broad use of power as the driver of all activity is inherently flawed, asking if Foucalt’s analysis is also driven by the power structure. He notes that this framework can be used effectively for political purposes, to fence off criticism from others with differing views and to force others to consider societal or systematic components of social challenges instead of focusing on individual moral choices.

The author concludes the chapter by noting that modern identity politics can be a tactic used to help left-leaning partisans increase the sharing of equal rights, opportunities and outcomes for all members of less-privileged groups within the framework of the liberal state model. Or identity politics can be a threat to the liberal model, denying universal modes of comprehension and experiencing reality and promoting groups as the primary political actors. He notes that the hard right often takes this same point of view, denying the authority of science or elites, creating its own language, denying free speech, challenging facts and elevating racial and national groups above the rule of law and universal rights of individuals.

8. Are There Alternatives?

The author summarizes some of the major criticisms of liberal states from the right and the left. He acknowledges that liberal states are imperfect at delivering these desired outcomes, even when they might be broadly accepted by the citizenry. He does not really address the true strength of this criticism. He has three responses. Better results could be delivered within the existing system through more effective political strategies and improved rules. The far left and far right usually don’t offer structural solutions that are better conceptually or practically. The solutions that are offered are typically offensive to the liberal state’s individual protecting principles and a majority of the citizens’ political opinions.

Social conservatives say that the liberal state offers no moral core beyond a soft nationalism, universal human rights, rationality, tolerance, respect for the rule of law, deliberation and compromise. The state “allows” morality and allegiance to groups but does not promote them. Hence, society has weak communities, low trust, diluted morality, limited responsibility and the absence of any overarching purpose. The bureaucratic state tends to overreach, prioritizing secular over religious views and empowering judicial and administrative actors to intrude on individuals. Unchecked market capitalism undermines family, community and tradition. The emphasis on individual rights undermines the efforts of groups to maintain ethnic, religious or other group cohesiveness.

Progressives focus on the lack of progress on addressing equal rights, opportunities and results for the broad population, but especially marginalized groups.

10. Principles for a Liberal Society

A. The quality of government matters, as does trust and support.

B. Inequality of opportunity, rights and outcomes matters.

C. Federalism is an important tool for controversial, non-critical issues.

D. Freedom of speech is a core value that supports other freedoms.

E. Privacy is a core right requiring protection.

F. The scientific method and rational problem solving matter.

G. Individual rights are fundamental. Group rights are problematic.

H. Human autonomy/independent choice is not a trump card. Groups, ethics, morality, nation matter too.

I. The liberal state rests upon the commitment and participation of its citizens.

J. Moderation is a virtue.
Good News: Healthy State & Local Government Finances

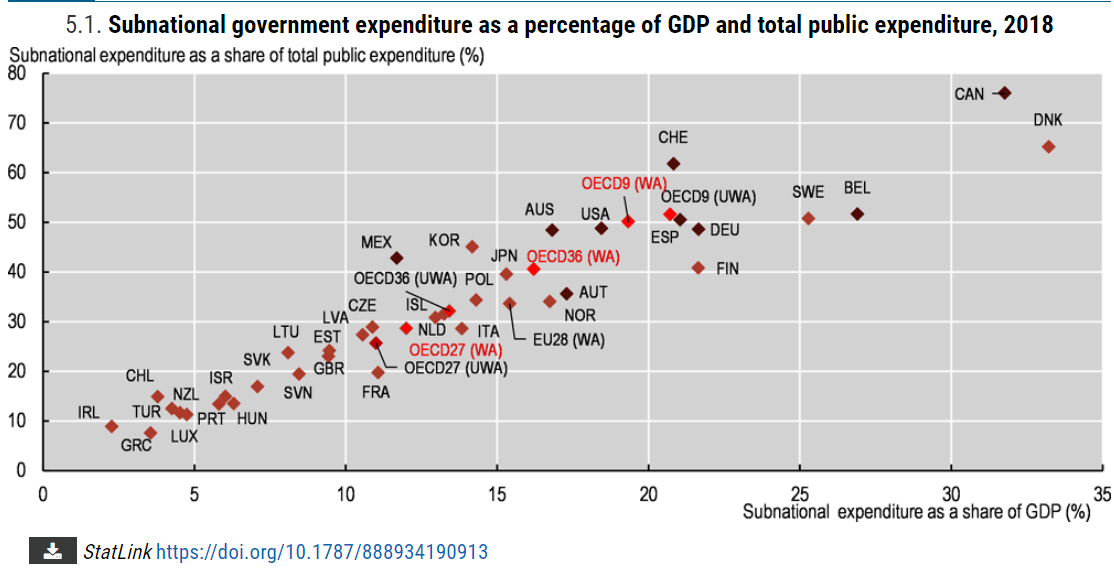
https://www.oecd-ilibrary.org/sites/c6217390-en/index.html?itemId=/content/component/c6217390-en

One-half of US government spending is managed at the state and local level. Only 3 OECD (developed economy) countries have a higher share at the local level. The median level is one-third of the total and some countries limit local spending to just 10-20% of the total. The US federal government model ensures that a significant share of government is managed closer to “the people”, which is even more important today with 330 million people than it was 200 years ago.

State and local expenditures as a percentage of GDP is 19% for the US, on the high side compared with other OECD nations as expected based on the 50/50 local/national split.

Government employment is even more concentrated at the more responsive state and local government level. State and local government employees comprise three-fourths of total government employment. This total increased from 21 to 23 million across 20 years while total US employment grew from 132 to 152 million. The share of government to total employment eased down from 16% to 15%. Note that this is much lower than the 38% government share of GDP.

https://fred.stlouisfed.org/series/PAYEMS#0

Federal government employment has been essentially flat for many decades.

https://www.cbpp.org/research/state-budget-and-tax/its-time-for-states-to-invest-in-infrastructure

Setting aside land and defense assets, states and local governments hold a supermajority of government assets.

https://en.wikipedia.org/wiki/Government_spending_in_the_United_States#/media/File:Federal_state_local_percent_of_gdp.webp

The share of total government spending to GDP is the most important ratio to track. Since the 1960’s the federal government has moved spending responsibilities to the state for many programs. Spending drifted up to 25% of a growing post-war GDP by 1966. The Vietnam War and the Great Society programs pushed this up to 29% in 1975. The oil crisis, Japanese competition, inflation and recession pushed it up to 32% in 1976. Spending was still 33% of GDP 30 years later in 2007. The Great Recession drove spending up to 40% of GDP and then it declined back to 34% in 2014. State and local government spending has been relatively constant since 1976.

https://www.usgovernmentspending.com/local_spending_chart

Local government spending reached its modern level at 9-10% of GDP by 1990 and has mostly remained at that level.

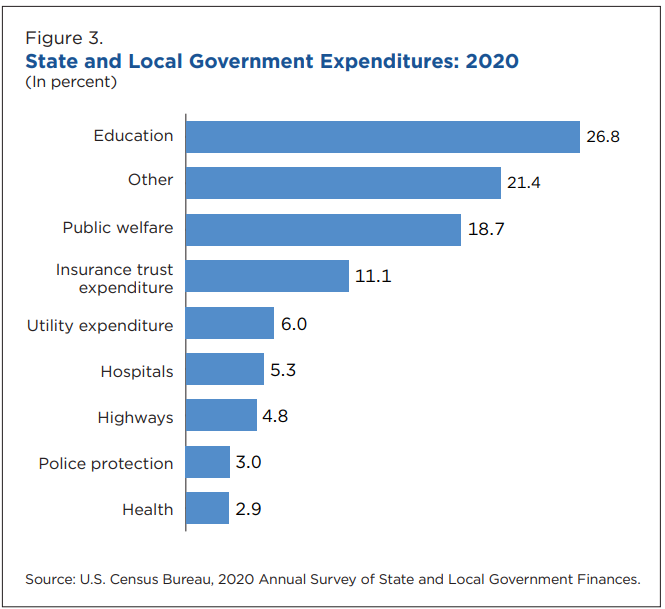
https://www.urban.org/policy-centers/cross-center-initiatives/state-and-local-finance-initiative/state-and-local-backgrounders/state-and-local-expenditures

federalism.us

https://www.pgpf.org/budget-basics/how-is-k-12-education-funded

State and local governments provide a wide variety of services.

https://fred.stlouisfed.org/series/L319411A027NBEA

States and local governments routinely deliver solid budget surpluses in normal years and greatly exceeding the deficits encountered in recessionary years. State and local governments rely more on property and sales taxes which do not vary as much as income taxes. States have proactively reduced spending budgets whenever they have encountered recessions.

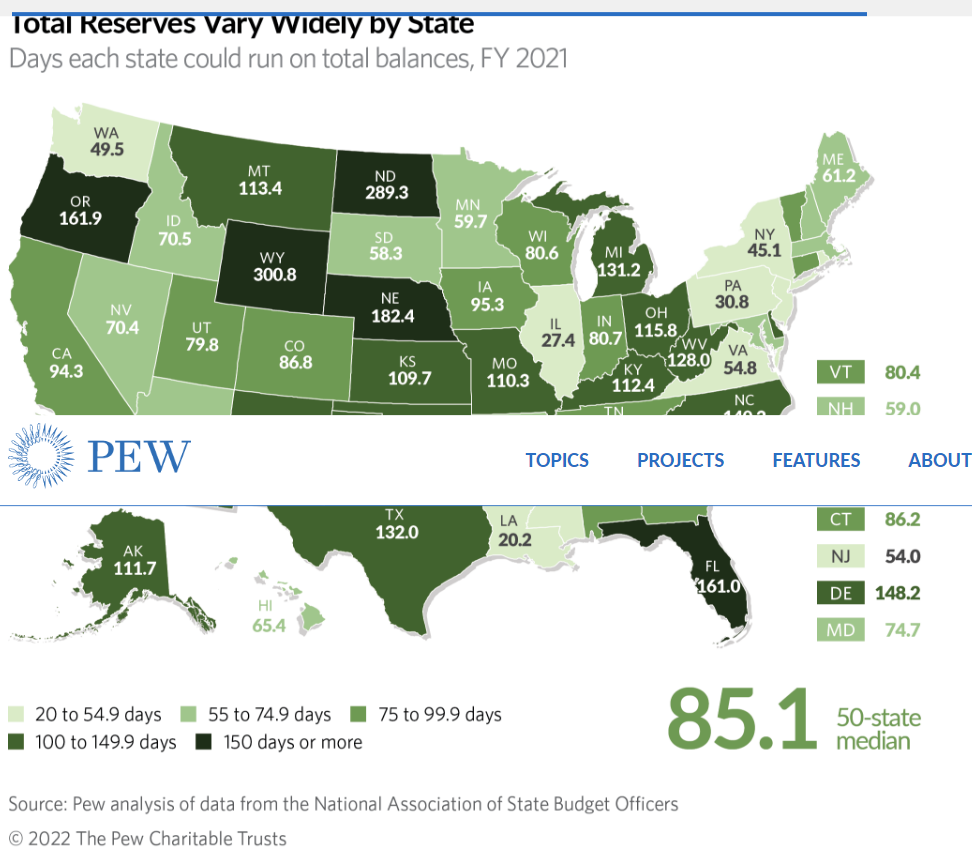
https://www.pewtrusts.org/en/research-and-analysis/articles/2022/05/10/budget-surpluses-push-states-financial-reserves-to-all-time-highs

States have built up a nearly 3 month cushion of reserves to buffer recessionary periods. States and local governments did much better during the pandemic recession than anyone expected. They reacted quickly to ensure fiscal stability and found ways to put the federal government transfers to good use. Some states have provided rebates to their taxpayers.

https://www.pewtrusts.org/en/research-and-analysis/articles/2021/10/15/states-financial-reserves-estimated-to-surpass-pre-pandemic-levels

https://fred.stlouisfed.org/series/SLGTFFQ027S

https://fred.stlouisfed.org/series/SLGTANA027N

State and local governments have continued to accumulate valuable assets, especially in the last 10 years.

States have generally improved their credit ratings since 2006, before the Great Recession. At that time, 9 states had the very highest AAA rating. 39 held very strong AA ratings. Just 2, Louisiana and California held “upper medium” A ratings. Recent data shows 7 more states, for a total of 16, at AAA ratings. 29 have strong AA ratings. 3 are at single A: Pennsylvania, Connecticut and Kentucky. 2 have fallen a step lower to BBB: Illinois and New Jersey. The median rating has improved from AA to AA+.

https://en.wikipedia.org/wiki/List_of_U.S._states_by_credit_rating

States have improved their pension fund percentage funding ratios, although some states remain at some risk of defaulting on their obligations.

https://www.urban.org/policy-centers/cross-center-initiatives/state-and-local-finance-initiative/state-and-local-backgrounders/state-and-local-expenditures

federalism.us

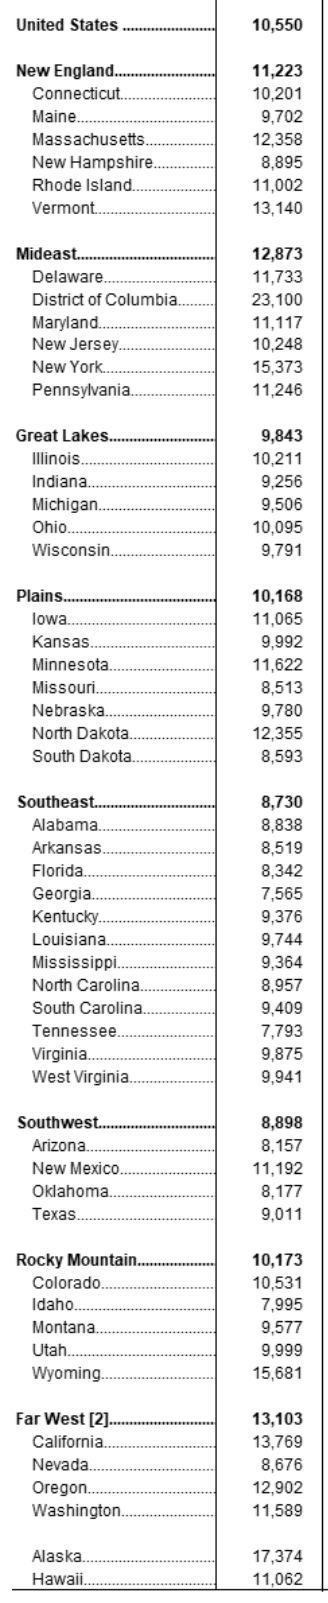
https://www.taxpolicycenter.org/statistics/state-and-local-general-expenditures-capita

State and local government spending per capita varies widely, reflecting local preferences. The mideast and far west are 15% above the national average while the southeast and southwest are 10% below the national average.

State spending varies even more widely. The national average is $6,900 per capita. California is 12th highest at $9,000 but neighbor Washington is much lower at $7,000 (26th). Massachusetts is also at $9,000 but its neighbor New Hampshire is at a very low $5,000 (46th). New York is lower than might be expected at $8,600 (15th). Nearby New Jersey, Pennsylvania and Virginia spend $7,200-7,500, a bit above the national average. Michigan, Ohio and Illinois spend less than the national average at $6,100-6,300, but nearby Indiana ($5,500), Kentucky ($8,500) and West Virginia ($10,300) have much different priorities. Georgia ($5,700), Alabama ($6,300) and Mississippi ($6,700) spend less than the national average. Texas spends only $4,700 per capita (48th) while its neighbor Arkansas spends $9,200 (10th). Florida is the lowest spending state at just $4,000 per person, an amazing 42% less than the national average.

Another way to look at these differences is to compare the spending of 5 states. Rhode Island $10,400 (6th), Kentucky $8,500 (16th), Washington $7,000 (26th), Colorado $6,200 (36th) and New Hampshire $5,000 (46th). Rhode Island spends twice as much on state government than New Hampshire, a few miles away. This is the range in the US, reflecting vastly different local priorities.

Summary

In our federal system, state and local governments are called upon to manage one-half of total government spending. They routinely deliver budget surpluses and adapt during recessions, even the pandemic driven recession. They have accumulated significant real and financial assets to buffer difficult times. They have managed pension liabilities appropriately and improved their bond ratings and ability to borrow. They have taxed and spent to match local preferences. In aggregate, their spending has remained at the same percentage of GDP for many years.

Firms and Jobs 3: It’s Complicated

The relationships between firm size, age, growth, survival, death, locations and job creation and retention are many, complex and politicized. However, the core relationships expressed in my 2 recent posts are well supported by data and theory. I’d like to share more background information.

The 10-year job survival rate for startups is roughly 80% and has improved in the last 10 years. However, the FIRM survival rate is much lower. The surviving firms, through economic natural selection, grow rapidly from a low (4 average employees) initial base.

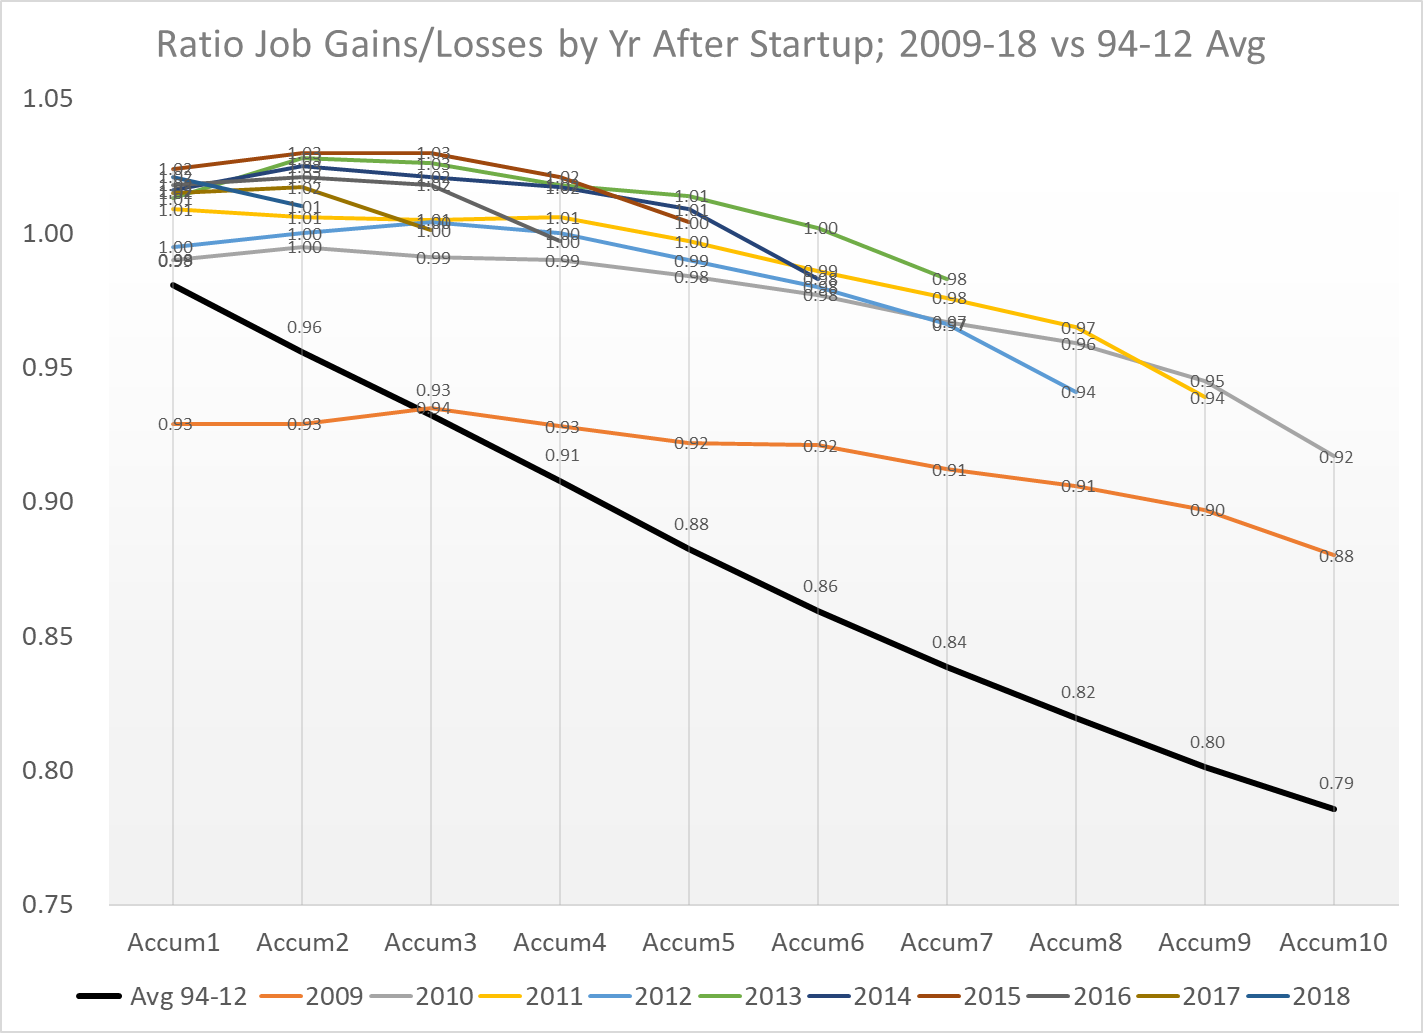
This study of 2011-14 highlights the initial start-up job surge, followed by 10 years of net job attrition and then modest net job growth by mature firms when low firm death rates (5%) are exceeded by decent levels of net jobs added.

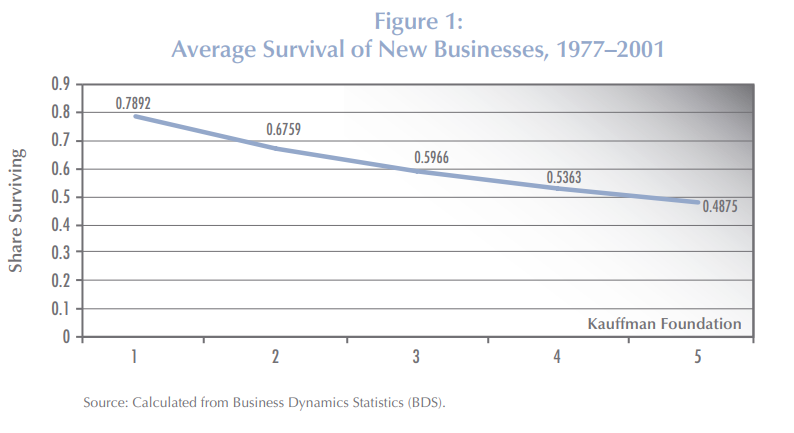
The Small Business Administration (SBA) reports the average firm survival rates for 1994-2019 as roughly two-thirds for 2 years, one-half for 5 years, one-third for 10 years and one-fourth for 15 years.

My review of the 10-year data confirmed the 33% rate for most of the period, with an increase to 36% for firms that began after the Great Recession in 2010-12.

https://www.chicagobooth.edu/review/surprising-numbers-behind-start-survival-rates

This post-recession improvement was widespread, across most industries.

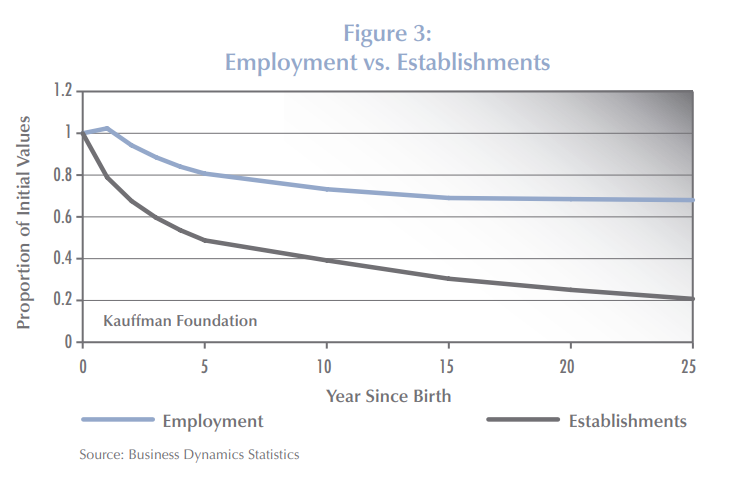
In 2010, Kauffman Foundation researchers summarized the detailed Business Dynamics Statistics (BDS) data, showing the relatively slow decline in net added employment from 100% initially to 80% at 5 years to 70% at 15 years and the rapid decline in the surviving firms rate to one-half at 5 years, 40% at 10 years and just 20% at 25 years.

Another Kauffman report from 2010 shared similar results. The universe of firms is dominated by young firms because the cumulative attrition makes “mature” firms quite rare.

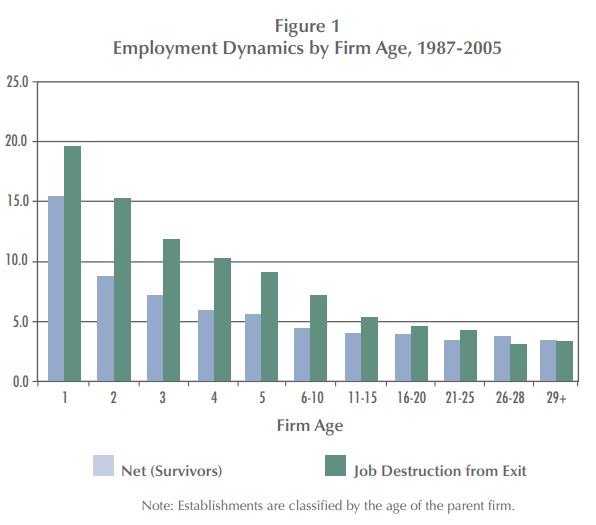
Another Kauffman report in 2009 summarizes this competition between dying firms killing jobs and surviving firms adding jobs. In the first 5 years, the firm failure rate is so high that it overwhelms the high job growth rate of those successful startups. In years 6-10, the death rate is still winning, but the total net job destruction is much smaller. For this 18-year data set, firm deaths exceed added jobs at every age, although 29+ year-old firms basically break-even. This is a critical insight when thinking about the claim that all or nearly jobs are added by startups. It is “true” due to the firm survival and jobs added rates at different ages. It is possible to have quite different results, with existing firms accounting for relatively more jobs, but that would require either the firm/establishment death rates to fall or the job creation rates of surviving firms to increase significantly. It looks like there has been some of that change after the Great Recession. This chart also helps to show that the “net, net” addition of jobs from start-ups, when considered as the sum of their first 5 years is in the 75-80% range, because the net jobs lost in those early years is only 5% per year, despite the more rapid loss of firms.

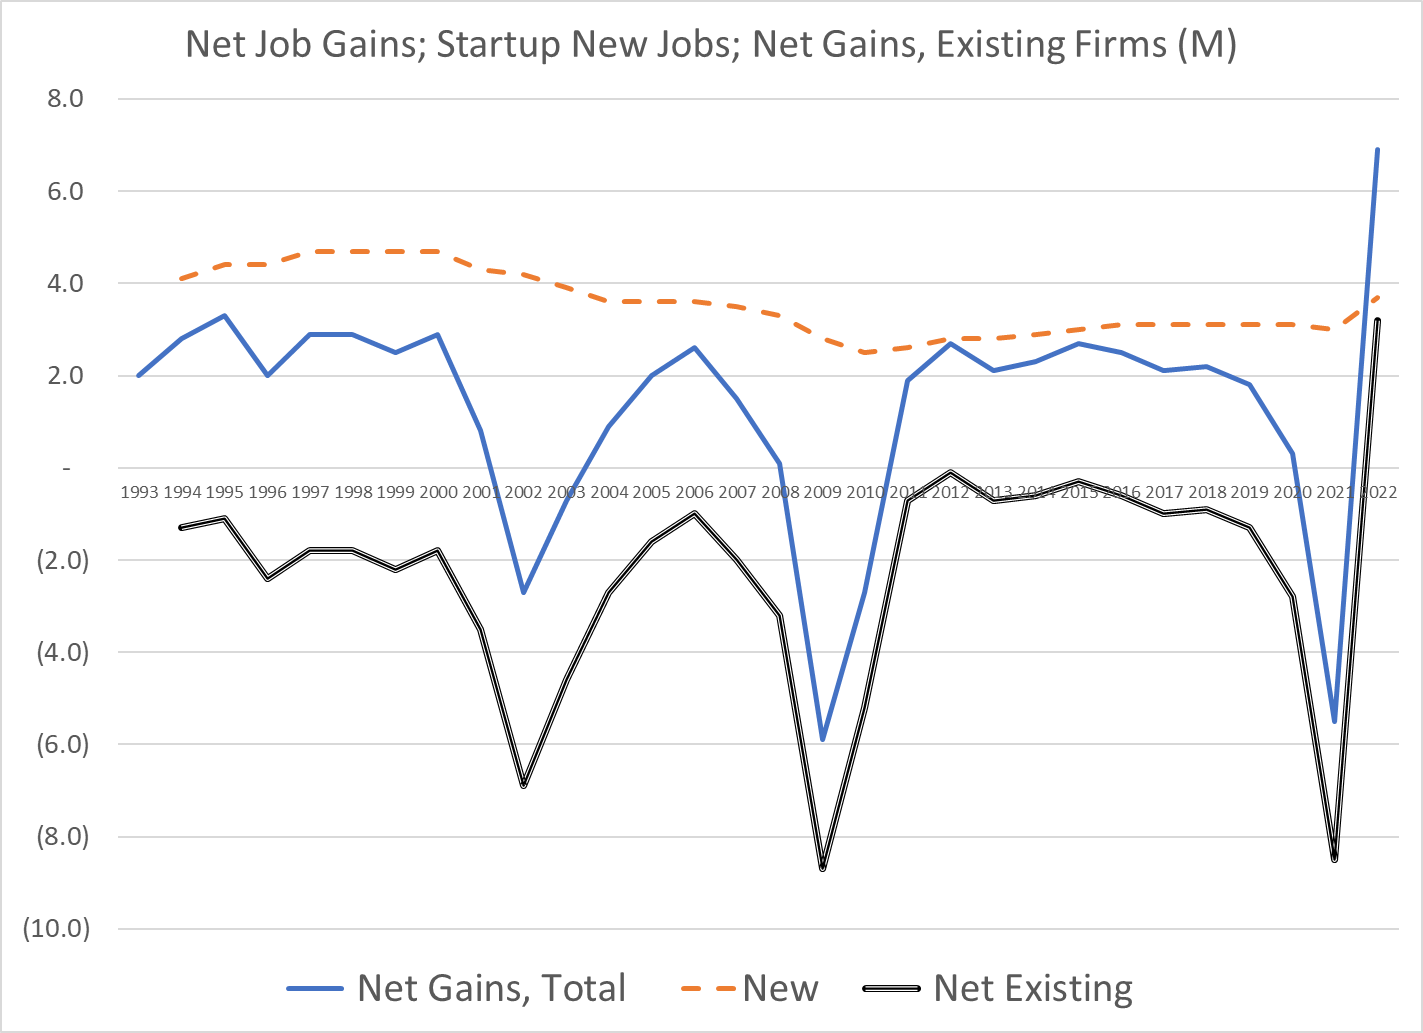
My summary of the last 30 years of data shows that startup firms do account for “all” new job growth. As others note, in a way this is almost “by definition”, because this is the only age group that only has “adds”, but no “losses”. It always must be positive. As we’ve seen in the details on job departures/hires, jobs created/lost, firms created/lost and establishments created/lost the positive and negative flows tend to be “roughly equal”. Hence, even a single year which is not burdened with an offset will stand out as the “big winner”. So, on the one hand we can discount the critical, essential, vital role of startup job creation, but we can’t ignore it. It is a necessary part of the life cycle of firms that delivers a growing economy.

The 2010 Kauffman study combined the initial jobs created with the jobs lost in the next years to emphasize the vital role of startups, using 2007 data. Mature firms also made a small contribution to jobs added.

Click to access size_age_paper_R&R_Aug_16_2011.pdf

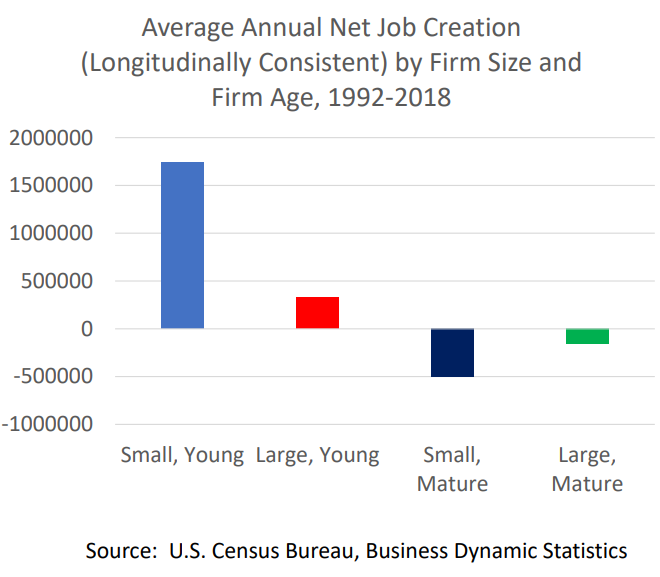
A follow-up report in 2011 by Dr. Haltiwanger summarized the data slightly differently but tells the same story. New firms, nearly all “small”, account for almost all job growth. Other small firms destroy jobs in their first 10 years at a high rate and as mature firms at a modestly high rate. Middle-aged firms lose jobs while successful firms grow to more than 500 employees and become large firms! Young large firms add a few net jobs. Old large firms lose a small percentage of jobs for this time period (1992-2005).

The same author updated the calculation with more recent data and found the same basic results.

https://www.census.gov/library/stories/2022/02/united-states-startups-create-jobs-at-higher-rates-older-large-firms-employ-most-workers.html

The central takeaway remains valid with more recent data across industries. The initial growth of jobs is not offset by the net losses in the next 5 years. Firms more than 6 years old do not add jobs overall.

https://www.bls.gov/opub/ted/2018/over-the-last-decade-large-firms-responsible-for-48-percent-of-net-job-growth.htm

A different set of data indicates that about one-half of net jobs added come from firms with 250 or more employees.

Another analysis indicated that nearly all added jobs were at “middle market” firms rather than startups.

https://www.bizjournals.com/bizjournals/washingtonbureau/2015/04/middle-market-companies-create-most-net-new-jobs.html

I don’t know how to reconcile these competing claims but expect that the time periods chosen, and firm sizes chosen, are keys to understanding the significantly different claims.

https://www.bls.gov/spotlight/2022/business-employment-dynamics-by-age-and-size/home.htm

The most recent BLS report shows that startups and large mature firms add jobs.

In the early papers the Kauffman Foundation explains that it is new firms that drive new jobs. There is an overlap between new firms and small size that makes an analysis based on size alone appear to say that “small firms create most new jobs”; but the “newness” logically comes first. Existing small employment firms tend to shed jobs through firm death or internal job reduction.

Click to access size_age_paper_R&R_Aug_16_2011.pdf

A simple model focuses on just the first 5 years of a firm’s life after the initial startup year and defines four buckets of job growth and loss due to adding new establishments or experiencing deaths versus internal job growth (up or down) at the survivors. All four buckets matter. New establishments are infrequent for startup firms. Deaths are a major job killer. Job creating firms outweigh job losing firms. But the net gains from internal job growth is less than the drag from firm deaths.

Kauffman also created a complete theoretical model of job changes through time based on the key parameters and demonstrated that the model was a good match with the observed relative consistency of the parameters and the net output of jobs created. In a prior life, we called this the “layer cake” graph, using it to explain the composition of revenues or profits in a business based upon the year of customer contracts signed or new products introduced. At any point in time, there is a history of additions of various ages. Employment tends to decline over time based upon the combination of firm deaths, establishment gains/losses and internal job growth. Each year a new group of firms is added, all with job gains in the first year. This group too follows the pattern of job erosion in the first 5 years, smaller erosion in the next 5 years, close to break-even by age 20 and small net job creation for the mature surviving firms. Again, the parameters could be different, and the results would be different. But this framework provides economists and statisticians with the tools to analyze the components.

Another author created a dynamic model which illustrates how this process works through time.

https://www.cbpp.org/blog/startups-fuel-job-growth-animated

The Small Business Administration promotes the view that small businesses (less than 500 employees) are essential to the US economy and create a majority of all jobs. As noted above, startups are the key. Size is a byproduct.

https://bipartisanpolicy.org/blog/trends-in-new-business-creation/

In my earlier post I discounted the importance of the decline in the share of new to total firmsbecause the corresponding decline in failure rates and improved job creation by mature firms was still delivering solid annual job creation. However, this warning signal is worth monitoring together with the other measures. The Brookings Institution provides some other “warning signals” about the health of the new firm/job creating capacity of the economy in light of reduced measurable competition in many industries (a topic for another day).

Startup rates are down in most industries.

New firms account for a smaller share of total employment.

Business formation takes longer. Recent Kauffman reports shows that this trend has continued.

The entrepreneurship rate of college educated Americans has fallen most significantly.

One professor analyzed this and concluded that it was the result of American firms taking advantage of the low cost of capital and paying the higher salaries and incentives needed to attract and retain high potential employees. He says that job creation is happening more in existing firms and less in startups with no negative overall effect. He says that “marginal” (low return) entrepreneurs have been removed with little negative impact on the economy as a whole.

The slowdown in the new firm/job creation rate after the Great Recession attracted much attention from the media and politicians. Two representative articles are listed below, mostly bemoaning the decline of startups/small firms and the relative growth of large firms.

https://www.inc.com/magazine/201505/leigh-buchanan/the-vanishing-startups-in-decline.html

With the renewed emphasis on small firms and public policy to support them, others have responded by emphasizing the benefits of large firm growth and questioning the need to support/subsidize small firm growth.

https://thereader.mitpress.mit.edu/small-business-job-creation-myth/

https://hbr.org/2016/06/do-startups-really-create-lots-of-good-jobs

https://www.washingtonpost.com/business/on-small-business/who-actually-creates-jobs-start-ups-small-businesses-or-big-corporations/2013/04/24/d373ef08-ac2b-11e2-a8b9-2a63d75b5459_story.html

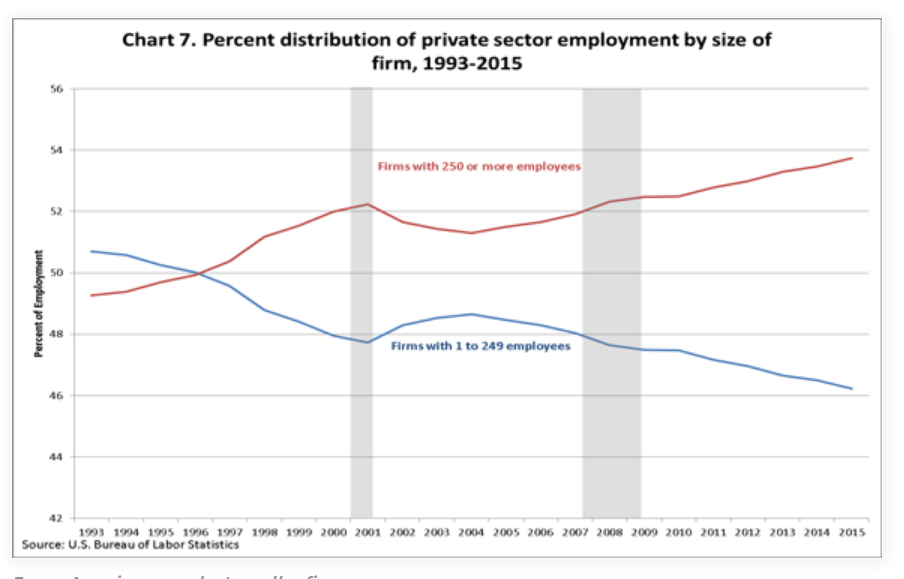
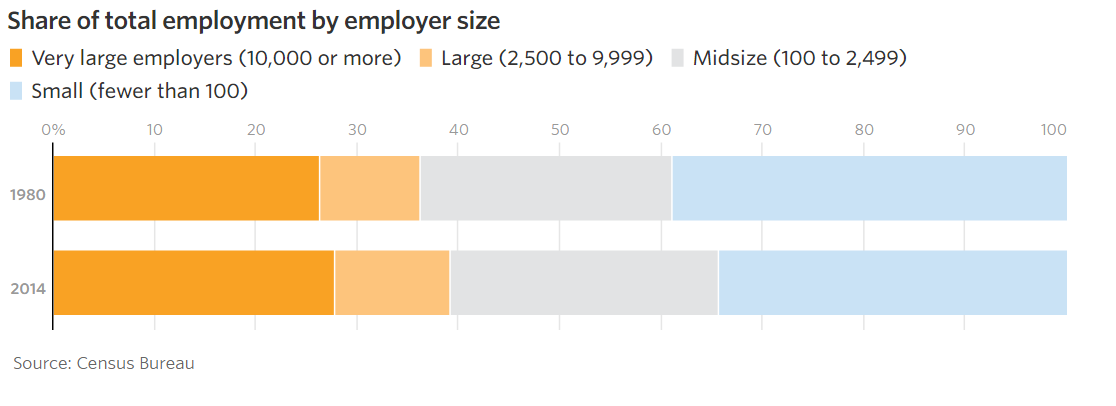
Using less than 250 employees to define “small business”, this article shows a 4% decline in small business share and 4% increase in large business share.

https://www.wsj.com/graphics/big-companies-get-bigger/

The Wall Street Journal reports that there are now more employees at very large (2,500+) versus small (<100) firms.

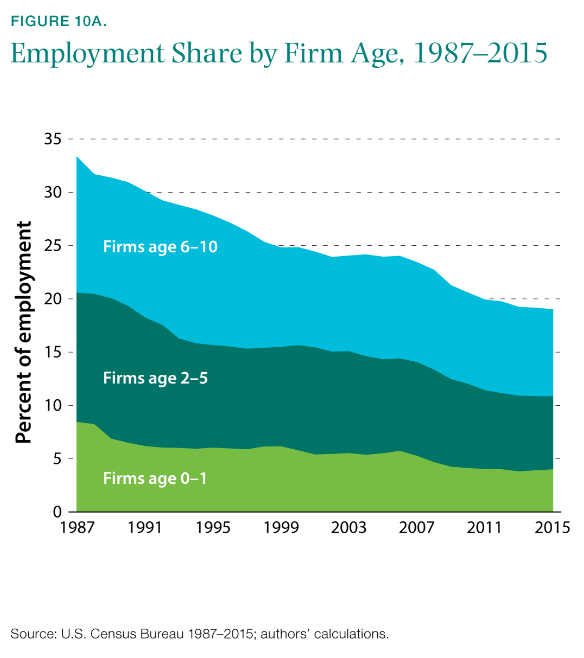
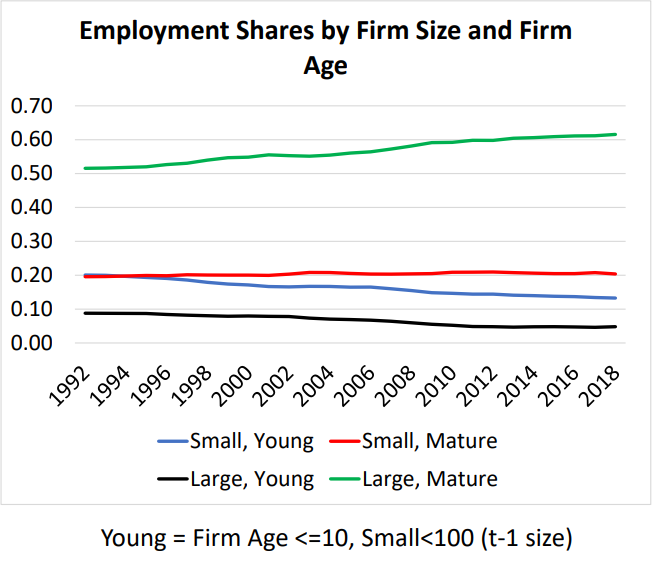
Professor Haltiwanger reports that large, mature firms have increased their share of total employees from 50% to 60% between 1992 and 2018. Both large and small young firms have lost offsetting market share.

https://www.census.gov/library/stories/2022/02/united-states-startups-create-jobs-at-higher-rates-older-large-firms-employ-most-workers.html

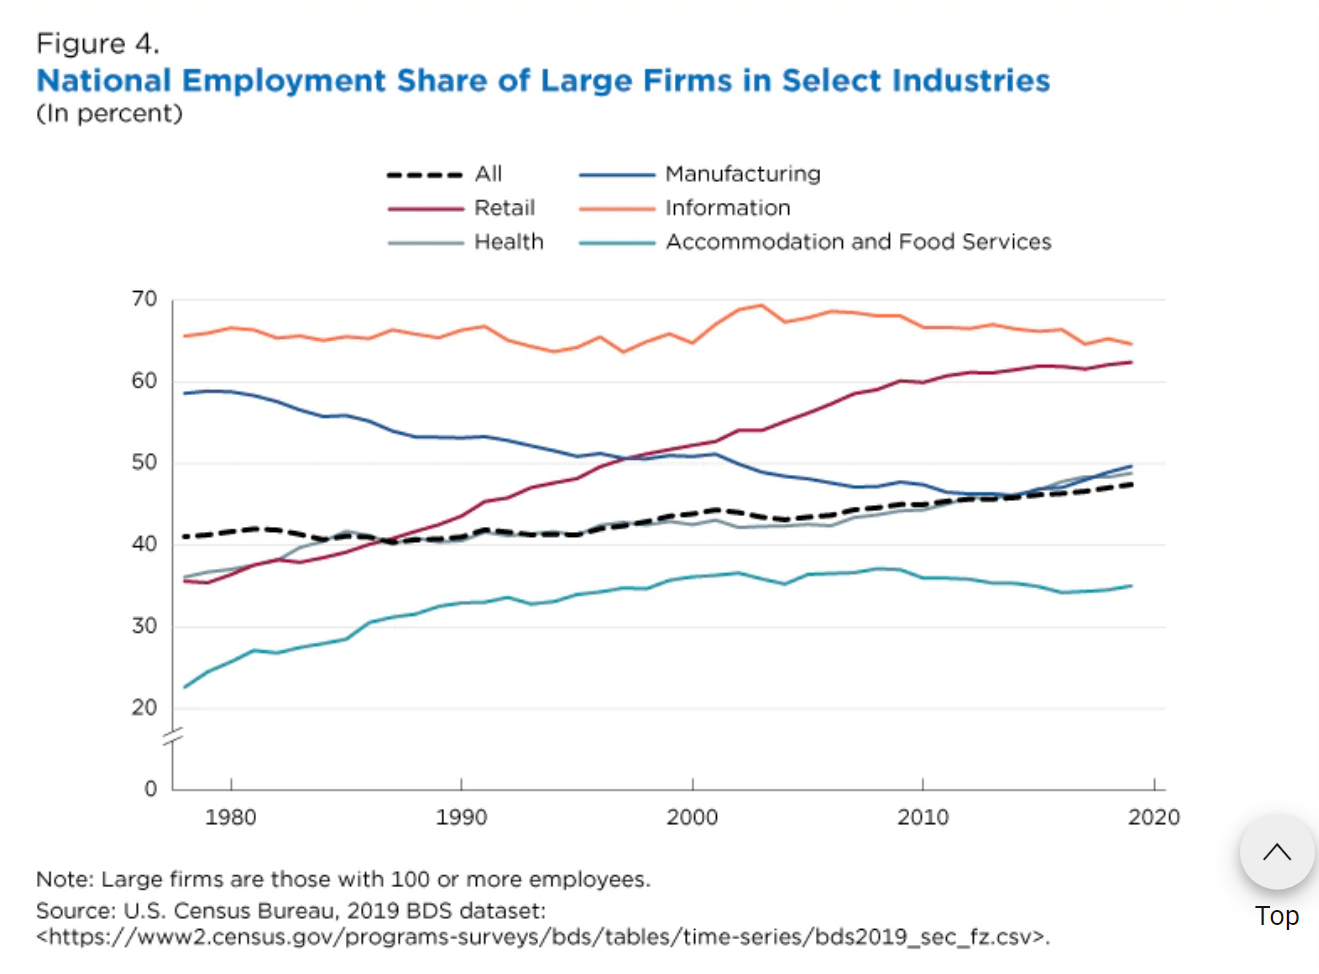
A recent Census Bureau article documents the increased employment share of older firms (6 years+) in many key industries.

It also highlights the increased concentration of workers in large firms in the retail, health care, accommodation and food services sectors.

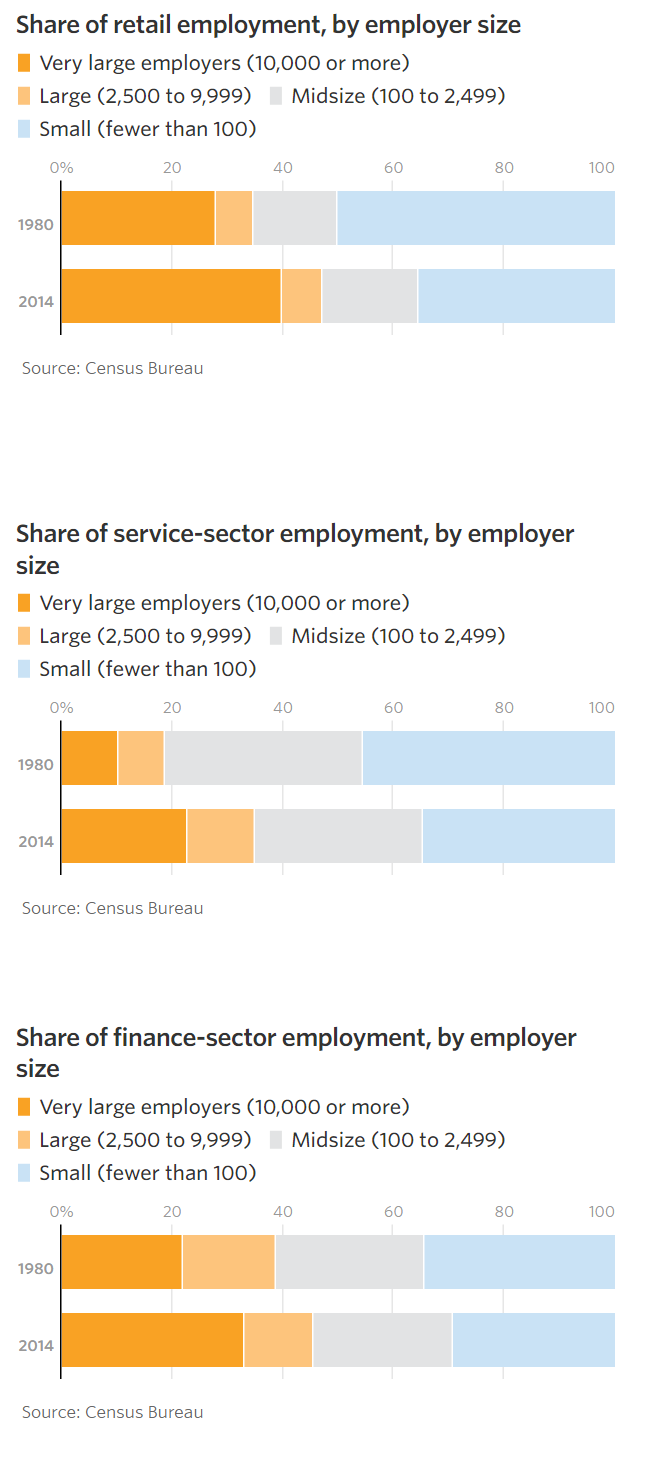
The WSJ articles itemizes the increased concentration of employment in large firms in the retail, services and finance sectors and documents that these are the growing segments of the economy.

Summary (It’s Complicated)

The Business Dynamics Statistics database provides researchers with the consistently defined and reported data since 1977 to document the key role of startup firms in adding net new jobs to the US economy. Startup firms are one part of an ecosystem of firm, establishment and job creation and destruction that plays out through time in relatively predictable ways. The death rates of young, middle age and mature firms play a similarly important role. The growth and decline of new establishments in existing firms matters. The internal job growth rates of young, middle age and mature firms matter. The relatively small size of startups compared to mature firms has an impact on job growth. Historical parameters are generally similar and change slowly, causing the layers of employment by firm age to be similar in this 50-year period. The model and framework for measuring firms, establishments and jobs is solid. Startup firms are essential, but they are not the only driver of success.

“Jobs created by firm size” is similarly shaped by all of these factors which describe the typical firm life cycle. Small firms are not superior job creators. New firms are job creators, and they happen to have small individual employment levels (4 on average), so small firms have higher measured rates of job creation.

In the last 10-20 years there has been a significant decline in the rate of new firm creation as a share of total firms. New firms created have not lost as many jobs due to firm deaths in their first 5-10 years. Mature firms continued to shed a disproportionate number of jobs during recessions, but after the Great Recession began to add more net jobs due to internal growth than they had in the prior 40 years. The overall number of jobs created has remained in the 2-4 million per year range across the 50 years.

The conservative SBA, Kauffman Foundation, WSJ and Republicans promote policies to ensure a thriving entrepreneurial environment for new and small businesses. The more liberal Brookings Institute, college professors and Democrats have an instinctive distrust of big business and concentrated economic power, so also lend support to some pro-small business policies. If job creation falters during periods of economic prosperity, this may be a rare place where bipartisan agreements could be reached to promote new firm and job creation.

Good News: Firms and Jobs

Many people complain that the US economy does not create enough new jobs or soon won’t create enough jobs or won’t create enough good jobs or … People worry about employment. Writers and politicians cater to that worry. Fortunately for us, the US economy creates jobs year after year after year, only briefly interrupted by increasingly less frequent and brief periods of economic recession. I’ll share the core numbers on healthy firms and new jobs and provide some context and history which indicates that this is inherent in the modern US economy. The economy is not relying upon any major political change or special insight to continue adding jobs. It just happens.

For 9 straight years, from 2011-2020, across 3 presidential terms and 5 congresses, the US economy added 2 million new jobs each year. In the 1980’s, it added 2-4M per year. In the 1990’s it added 3M per year. In the “oughts”, it added 2M per year. 30 years of expansion, 7 lesser years that averaged more than zero. 4 strong years for every 1 weak year..

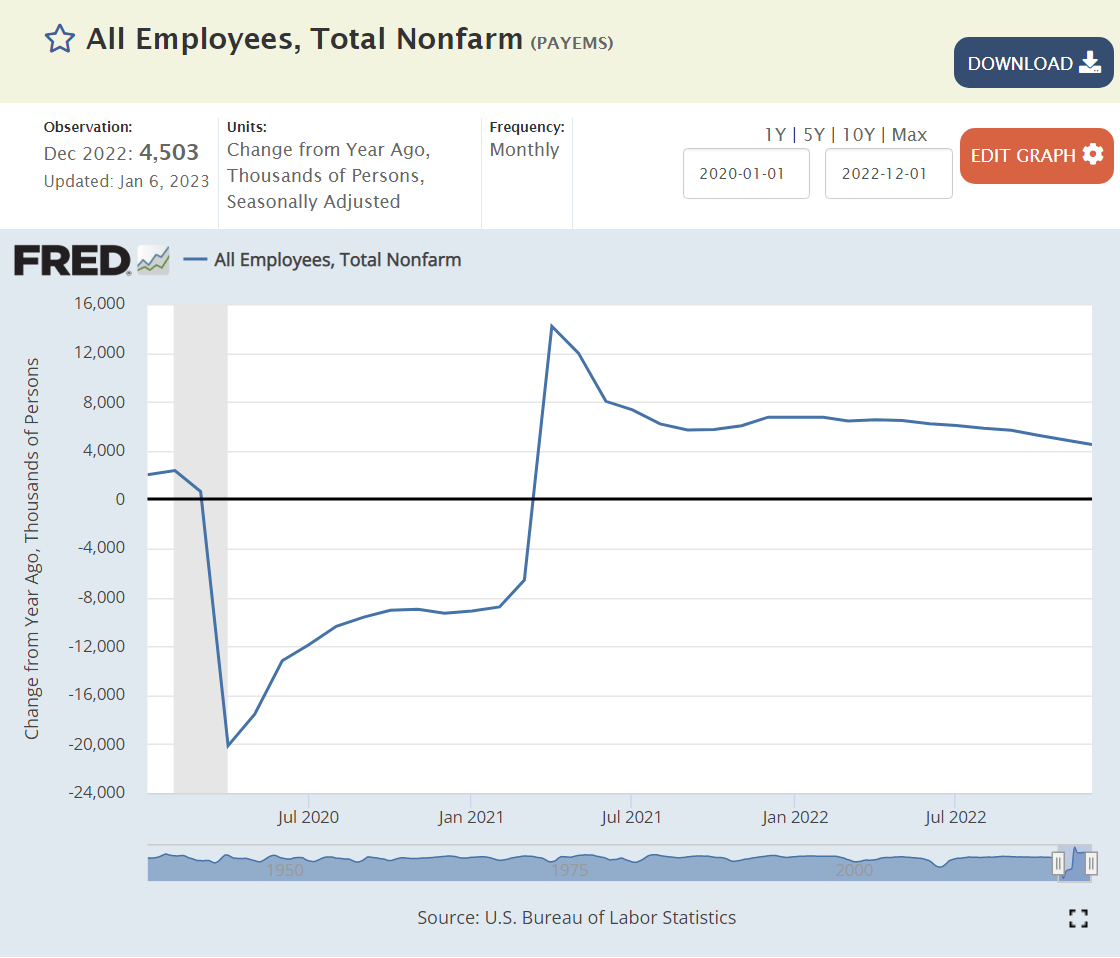
The recovery since the pandemic has been even stronger, starting at 8M new jobs per year in 2021 before sliding to 6M per year and most recently 4.5M per year.

My post earlier this week focused on the role of start-ups in driving job growth. I’d like to build upon that post.

The total number of firms in the US grew slowly in the last 40 years, from 3.5 million to 5 million. The growth rate was much faster prior to the Great Recession (2007-9). Much of this growth was accounted for by single employee firms. Despite this tame 1% growth per year, the economy was able to add more than 2 million jobs per year.

The number of establishments (locations) grew almost twice as fast, just under 2% per year.

The US economy requires some growth in the number of firms or establishments each year to drive job growth. Fortunately, it does not require heroic growth rates.

The number of new establishments added per year is remarkably consistent, averaging about 700,000 per year on a base of 5-7M. Of course, this means that the RATE of new establishments is shrinking, from 14% to less than 10%.

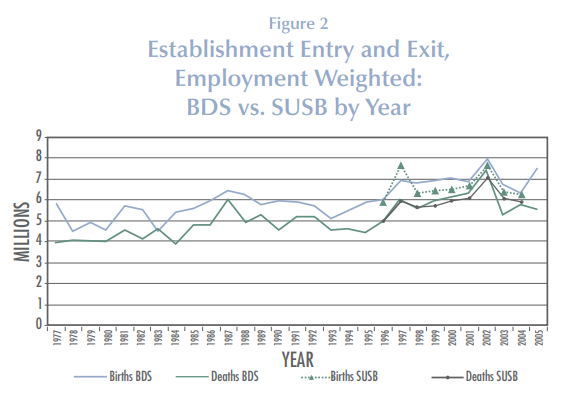
Establishment exits have increased from 500K to 600K to 700K before returning back to 600K per year. Big picture, 700K new establishments and 600K lost establishments each year across 4 decades.

Firm deaths have also been consistent at 450,000 per year.

Data calculated from BDS data. Direct graph not available.

Firm births have also averaged about 450,000 per year but present a different pattern. Firm births were much lower in the troubled time around 1980. Births ranged from 450-500,000 per year in the next 25 years. The Great Depression destroyed businesses, access to capital, personal net worth and aggregate demand. Hence, new firm creation dropped back to the 400,000 level. It recovered back to the 450,000 per year rate by 2015. As with firm deaths, the rate has fallen from 14%+ to less than 10%. Most importantly, the birth and death rates have been relatively consistent and have both been relatively flat, leading to a slow increase in the number of US firms.

https://www.bls.gov/spotlight/2022/business-employment-dynamics-by-age-and-size/home.htm

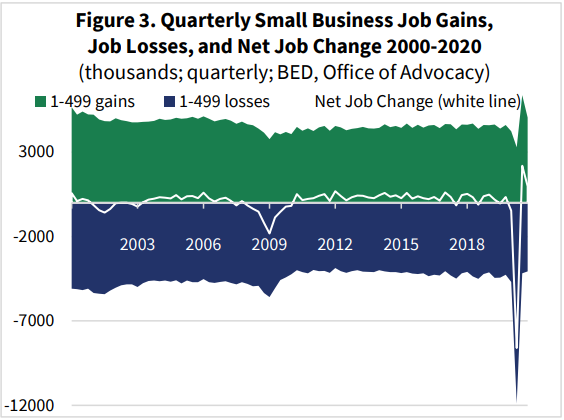
The BDS database shows that job gains and job losses generally move together, but that in a recession job gains fall and job losses increase. This is a very important result. Without active government or policy intervention, the economy creates 12-14M jobs each year and destroys 11-13M jobs each year. There is no guarantee that net jobs will be created in any given year, but overall that is the normal result.

https://bipartisanpolicy.org/blog/trends-in-new-business-creation/

Writers who wish to emphasize the decline of entrepreneurship focus on firms instead of establishments because of the slower growth rate. They emphasize the growth rate rather than the growth numbers because this is less positive. They don’t compare the growth and death rates or numbers, which move together. They focus on the aftermath of the Great Recession which did greatly slow firm creation, resulting in slower than historical numbers and rates of job creation from new firms. Nevertheless, the economy created 2M new jobs per year for 9 years. During that period, existing firms captured a larger than usual share of the job growth required to provide demanded goods and services.

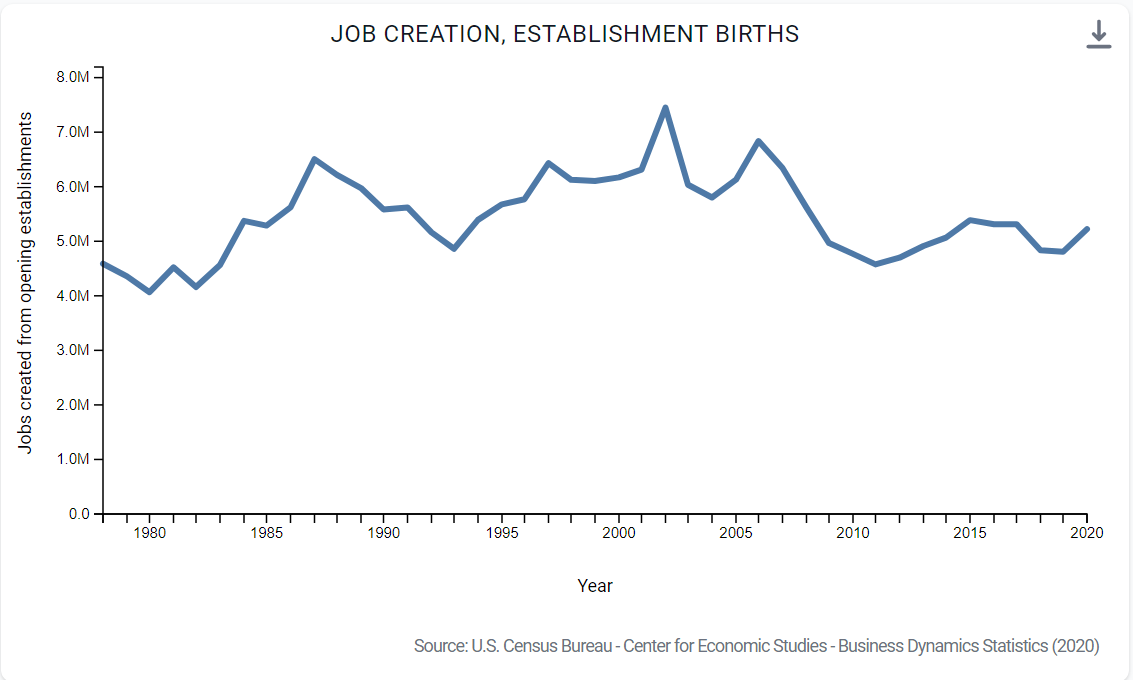
New establishments have driven 5-6M new jobs each year. The late nineties to early “oughts” reported the higher 6M per year figure.

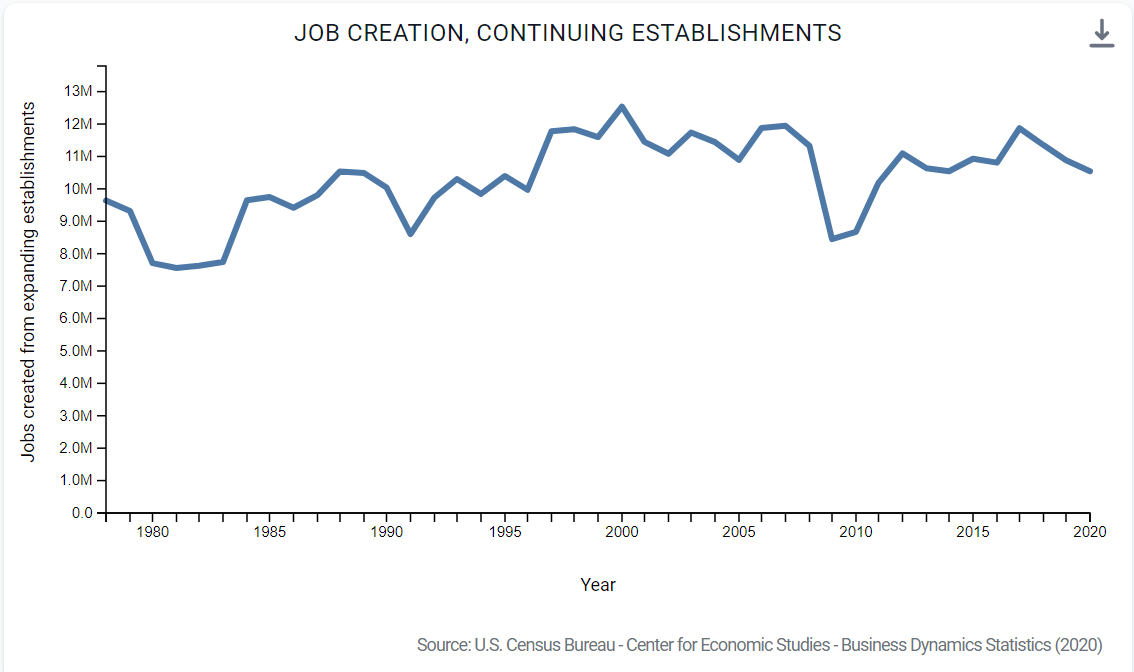
Existing (continuing) establishments have added 10-12M gross new jobs each year.

Establishment deaths (including firm deaths) resulted in 4-5M jobs lost each year.

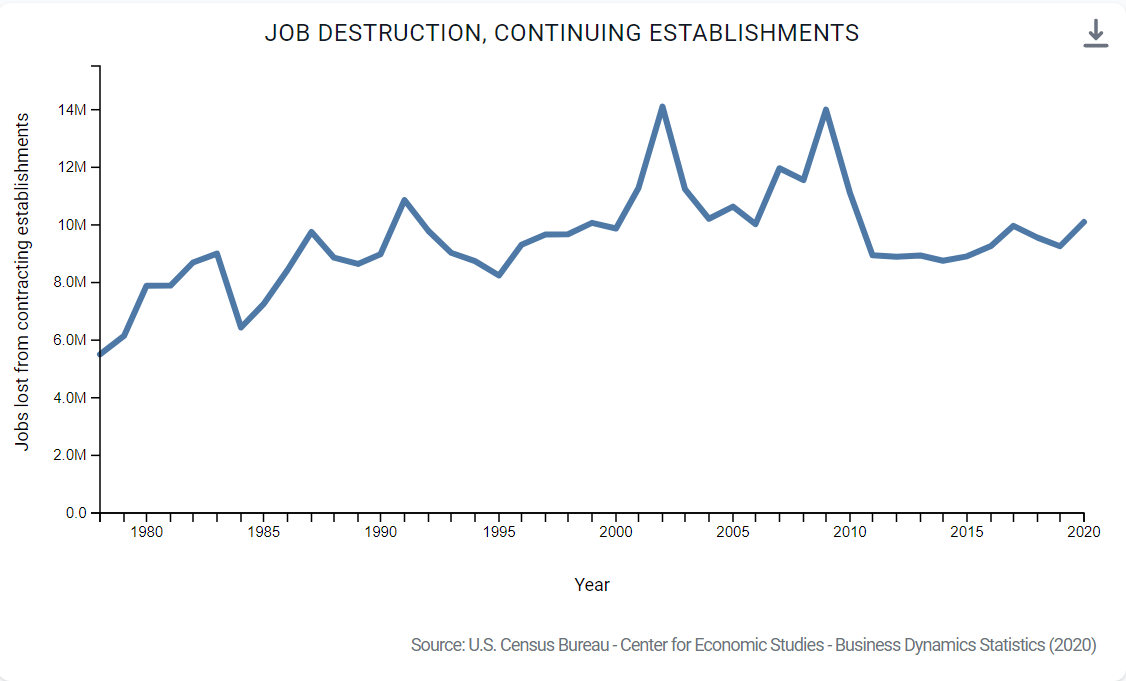
Continuing establishments trimmed 8-9M jobs each year, and many more during recessionary times. Although there are many moving parts, continuing firms eliminate more jobs than they create, especially during recessionary periods when they are adapting to lower demand. Firms die and they close locations, removing 4M jobs each year. New firms and new establishments add the new jobs required to fill the 2M net new jobs each year. This does not happen automatically or precisely, but overall, through time, the pattern is clear.

The US job market has grown from 90-150M positions during the last 40 years.

Firms hire 75M people each year. The typical job tenure is just 2 years.

Separations and hires generally move together. The net 2M jobs added annually is a small fraction of employment, hires, separations, gross job adds and gross job losses.

Establishment births exceed establishment deaths except during deep recessions.

New firms have high failure rates. Fortunately, firms that survive their first year have high percentage rates of new hires. They start with a small number of employees (4) and grow rapidly. The survival rate improves with the age of the firm and the employment growth rate of surviving firms tends to decline as they grow. The combined effect is that 80% of the new employees added by startup firms remain after 10 years. This employment survival rate has been improving in the last 15 years, partially offsetting the reduced number of start-up businesses.

https://www.bls.gov/spotlight/2022/business-employment-dynamics-by-age-and-size/home.htm

The first-year survival rate has remained roughly the same at 80% for 25 years.

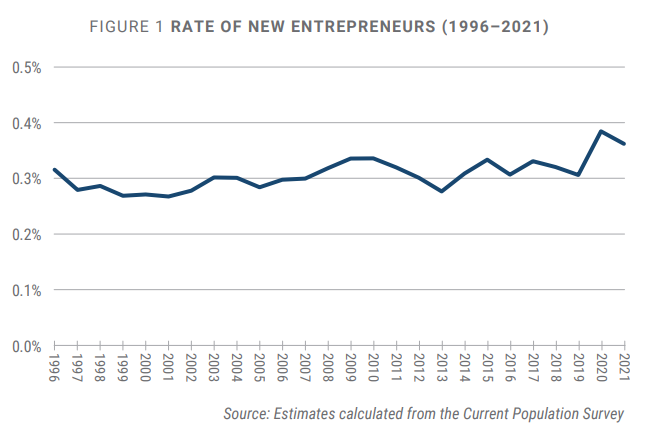
The percent of non-business owning adults who start a business each month has shown a small upward trend before jumping up in 2020 and 2021.

The ratio of new employer businesses to population dropped significantly after the Great Recession, but has recovered in the last 4 years.

The share of “new employer businesses” dropped after the Great Recession and has not fully recovered.

The number of application for new business tax ids increased significantly after the Great Recession and jumped by 50% after the pandemic.

The Census Bureau also tracks a subset of the total new business applications based upon industry classification that is a better predictor of actual businesses eventually started. This measure shows modest growth after the Great Recession and a 30% spike after the pandemic.

About 10% of new business applications become new businesses. Hence, the rate of new business formation to be reported for 2022 is expected to be very high.

https://www.silive.com/business/2022/08/new-business-applications-are-on-the-rise-heres-what-led-to-a-record-setting-year.html

https://www.nber.org/digest/202109/business-formation-surged-during-pandemic-and-remains-strong

https://www.oberlo.com/statistics/how-many-new-businesses-start-each-year

https://bipartisanpolicy.org/blog/trends-in-new-business-creation/

https://bipartisanpolicy.org/blog/trends-in-new-business-creation/

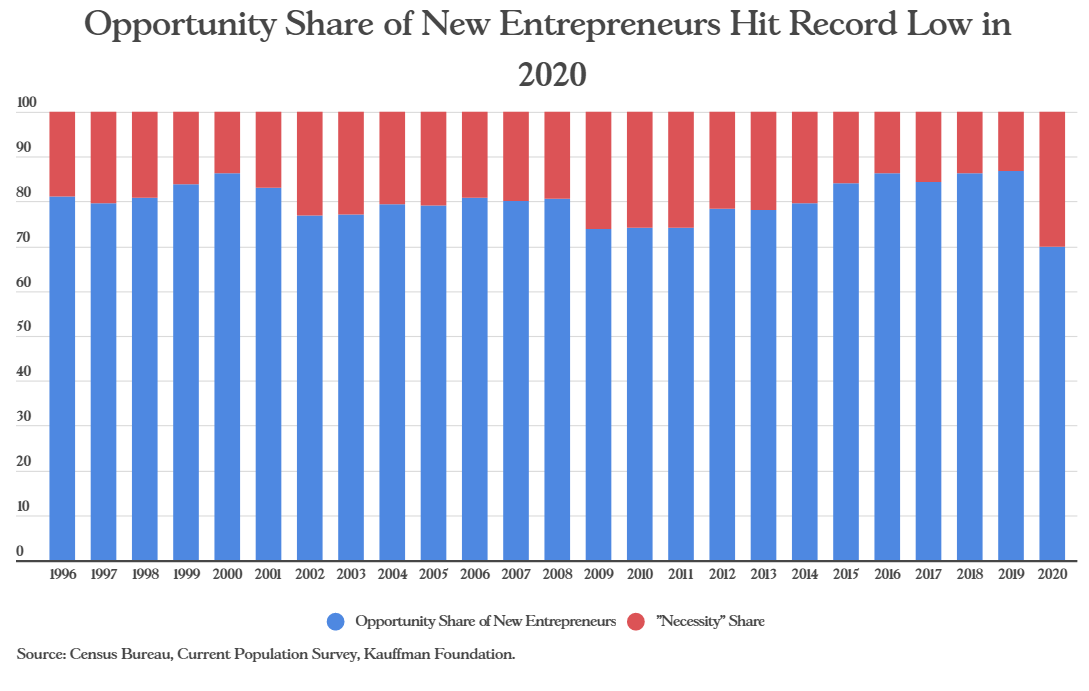
About 80% of new businesses are formed based on opportunity and 20% based on necessity. Kauffman estimates that 2020 business formation was 30% based on necessity.

Summary

The US economy continues to generate 2 million new jobs in each non-recession year, even more in boom periods like the last 2 years. Firms and establishments are born, grow and die. The net employment growth rate for established firms is less than zero in their first 5-10 years and then slightly positive. The annual death rate of existing firms and establishments is relatively low, but on a 150M employee base it is 4M per year. The new jobs added by startup firms and new establishments allow the total number of employees to grow in normal years.

There is no “iron law of employment” that requires new firms or establishments to be created in numbers greater than the job losses. There is no law that requires surviving young firms to nearly offset job losses by young firms that die at a high rate. There is no law that requires mature firms (10 years old+) to add new employees or to die at slow rates. But these results have been consistent or improving for the last 40 years. I look forward to continued success.

Inflation is Slowing

Brief Analysis Below Each Chart:

Since July, overall inflation is immaterial (1%), about 2% on an annual basis.

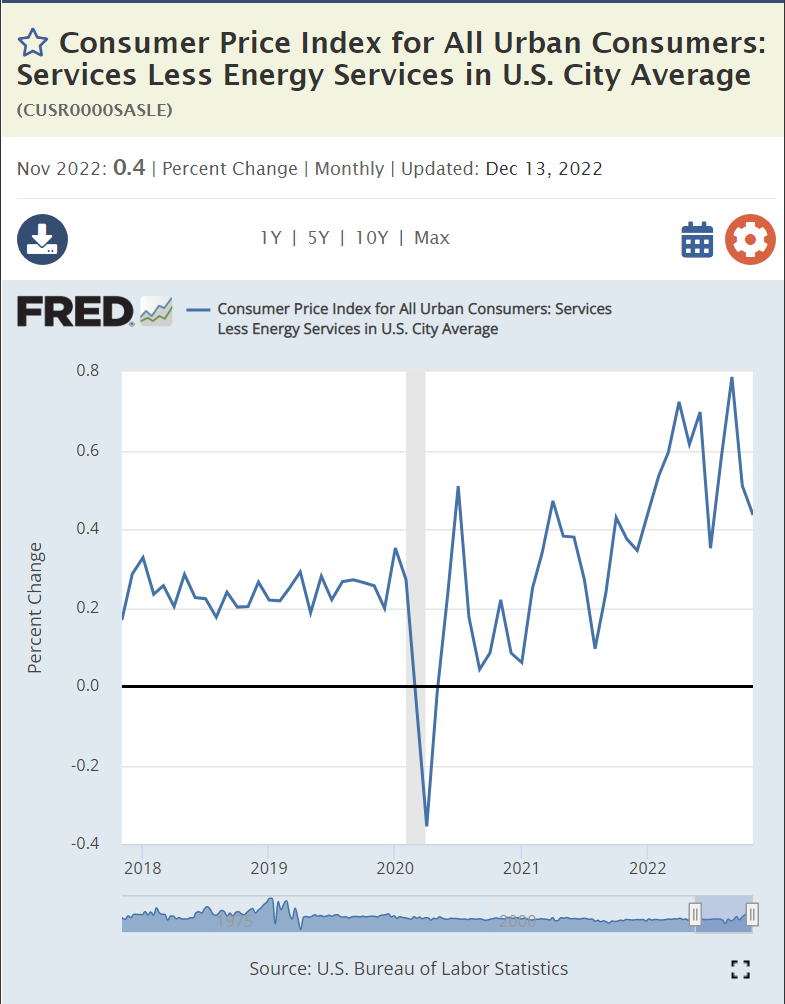
The Services sector is the most concerning, with annual inflation still running near 6%. The recovery from the pandemic started with the goods sector and then slowly rotated into the services sector as “in person” services re-emerged.

Since March, 2022 durable goods have reassumed their long-term price Deflation.

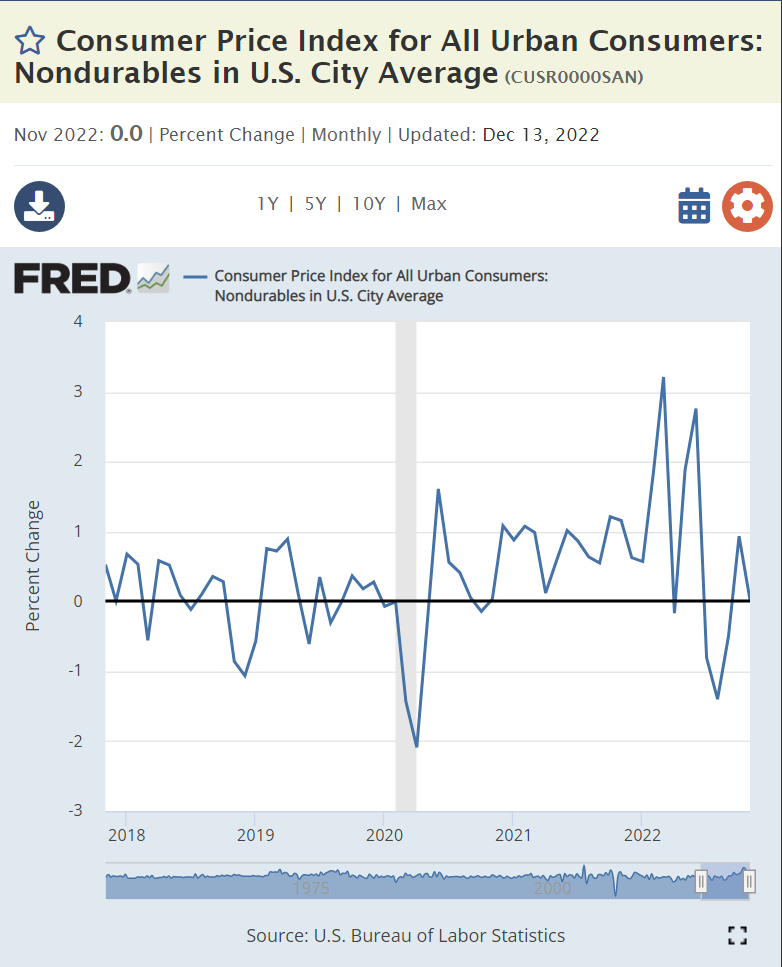
Nondurable goods are back to 0% inflation.

Energy prices are clearly falling now.

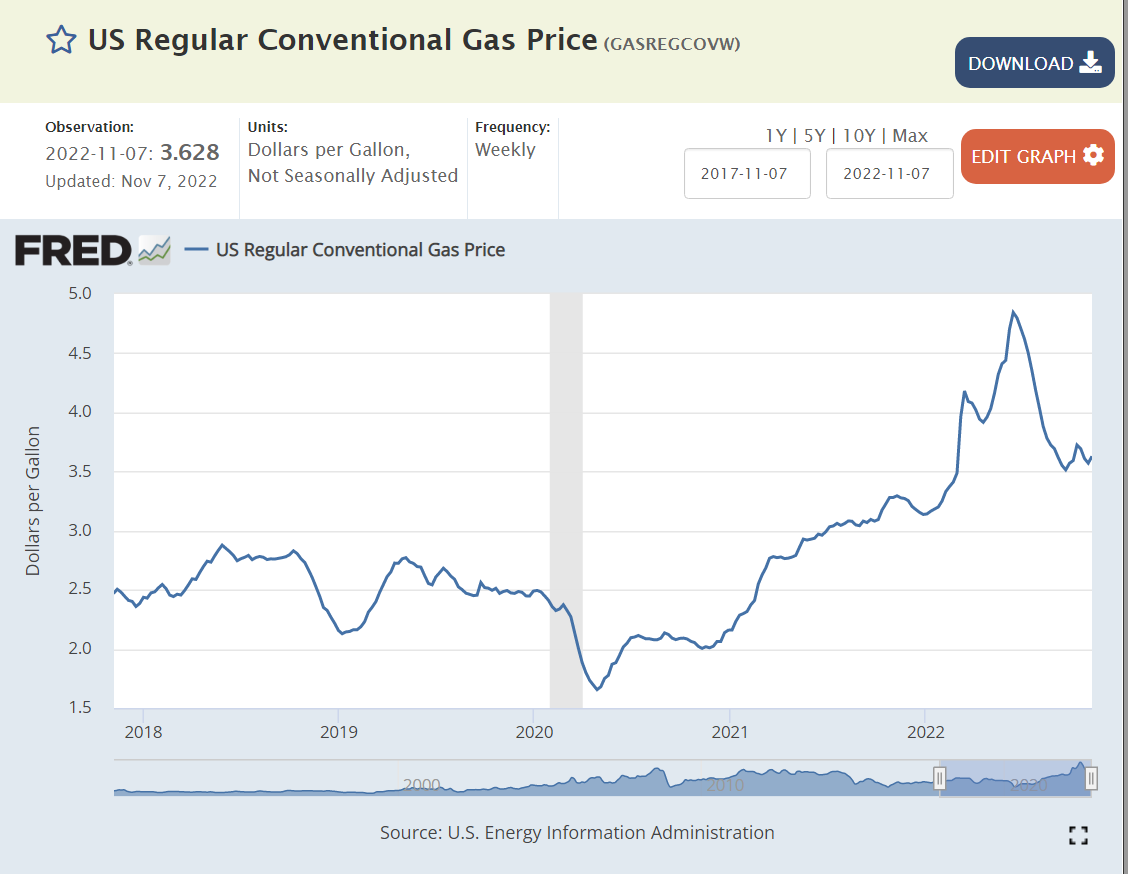
Gas prices have retreated back to $3 per gallon as quickly as they increased.

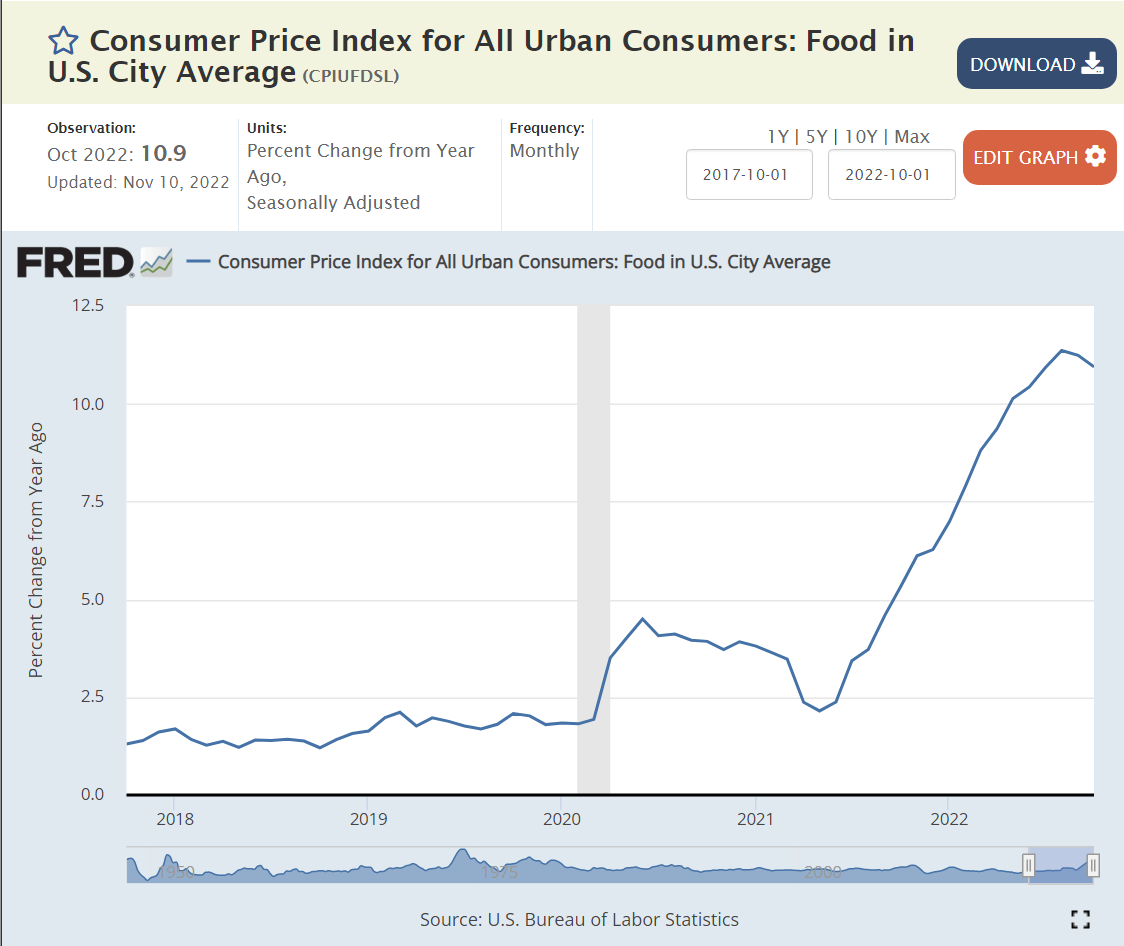
Food prices have fallen but remain abnormally high, growing at 6% annually. Global pressures may keep this category above normal during 2023.

Wage-push inflation remains a thing of the past. Real wages remain flat.

Strong economies with solid currencies are able to import cheaper goods and reduce domestic inflation.

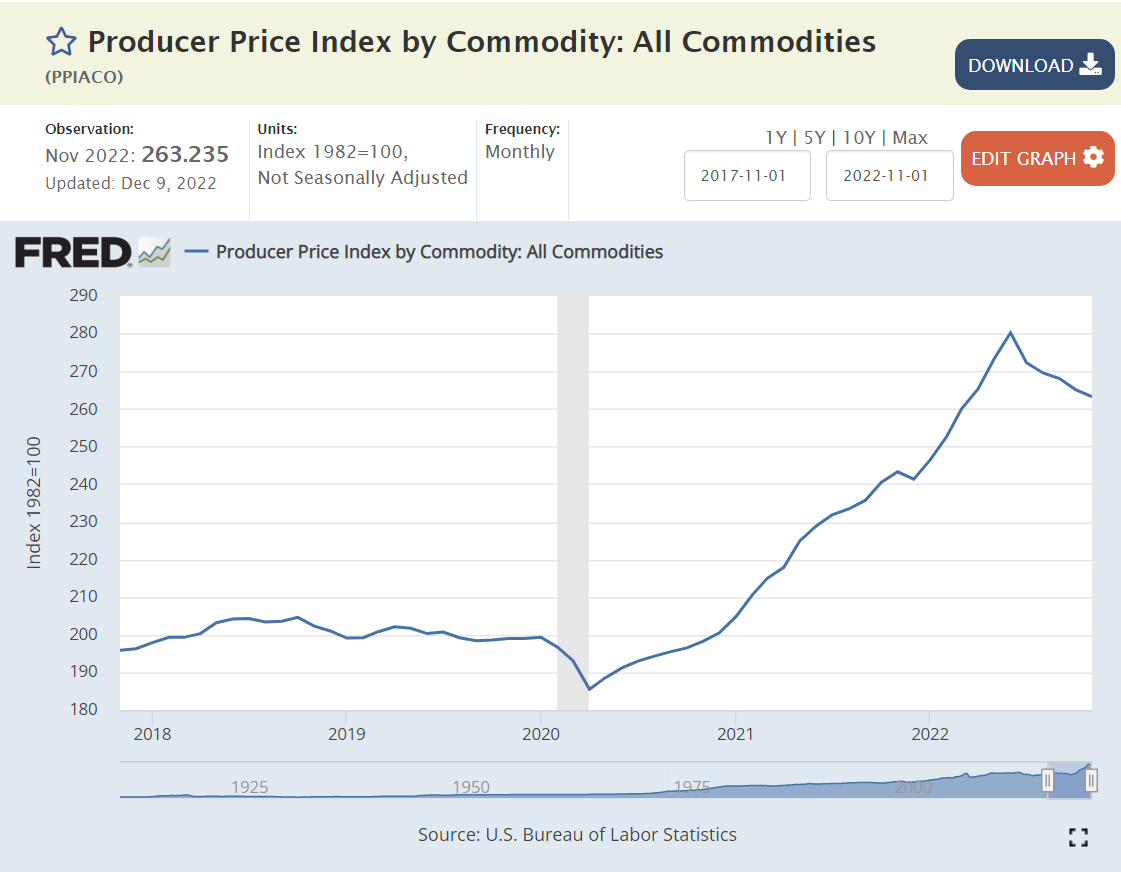
Producer prices have fallen by 6% from their peak.

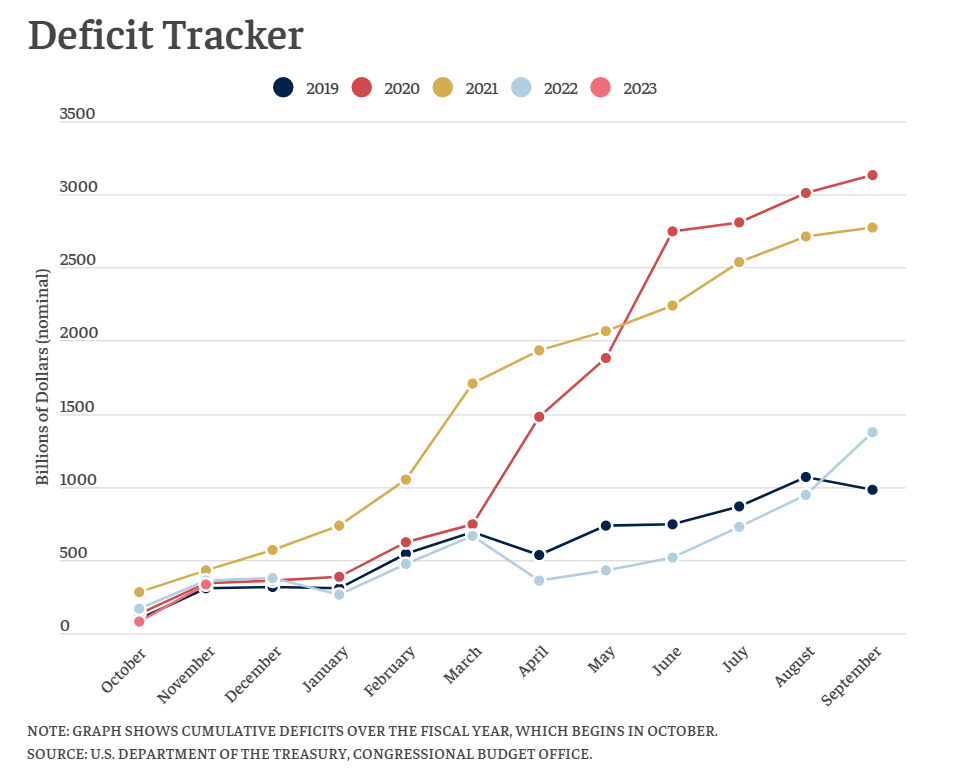
US fiscal policy for 2022 was at the same expansionary level as pre-pandemic 2019. I think it was a little too expansionary, but this level of deficit did not significantly drive the increased inflation in 2022. The budget deficit for fiscal year ending September, 2023 is expected to increase by a small amount, even though the latest official CBO forecast showed a smaller deficit.

https://www.cbo.gov/publication/58470

Monetary policy was very loose in 2020, attempting to offset the many threats to the economy. It has since been closer to “neutral”. There is no solid historical or theoretical basis to carefully predict the effect of this huge increase in the money supply two and a half years later.

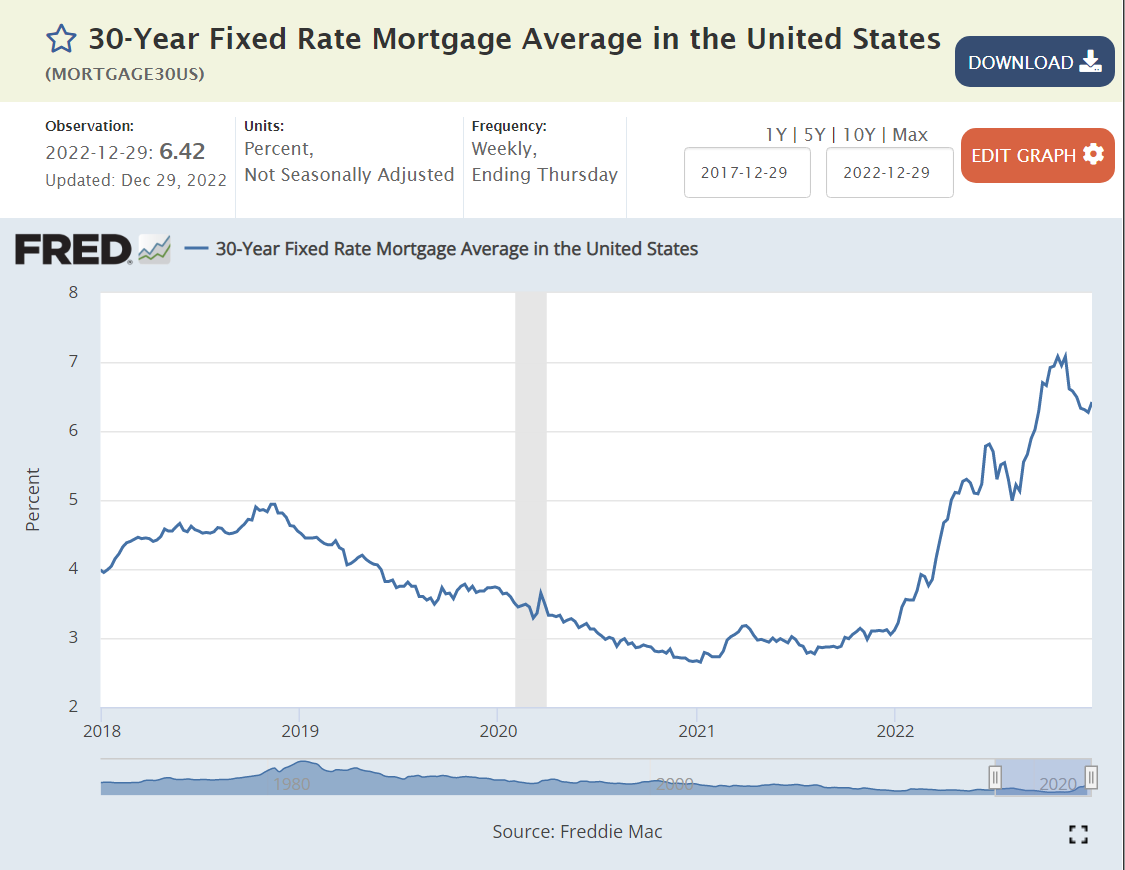
The Federal Reserve Bank has increased interest rates and the housing, stocks, bonds, construction and commercial investment markets have been impacted, slowing aggregate demand for assets, goods and services.

https://www.federalreserve.gov/econres/notes/feds-notes/excess-savings-during-the-covid-19-pandemic-20221021.html#:~:text=By%20the%20third%20quarter%20of,%241.7%20trillion%20by%20mid%2D2022.

The stock of “excess savings” which supported the rapid recovery from the pandemic peaked in early 2021 at $2.25T. It had fallen by 20% to $1.75B by the 3rd quarter of 2022 and continues to fall, reducing aggregate demand.

Summary

The scariest inflation scenarios are no longer plausible. Durable goods, nondurable goods, producer and energy prices are falling. Food and services prices remain elevated at 6% but are not in double digits and are not increasing. Real wages spiked briefly during the heart of the pandemic but quickly returned to pre-pandemic levels where they have remained.

The federal budget deficit in 2022 was the same as in 2019 when inflation remained low. Even with a slowing economy, the forecast 2023 budget deficit remains about the same as in 2022, not adding materially to excess demand. Monetary policy in 2022 has consistently been tighter and tighter, with the Federal Reserve chairman promising to “do whatever it takes” and highlighting the much greater negative consequences of inflation that does not return to the target level. Weakened fiscal and monetary policy should help to further reduce any remaining supply chain constraints in the global economy. The housing and capital investment sectors are declining. The impacts of changed monetary and fiscal policies are seen 6-24 months later.

Double-digit and accelerating inflation are no longer credible. Deflation is the rule in a large part of the US economy. Monetary and fiscal policies are tightening. Overall inflation is falling. The economy has already slowed, so we may even be entering a period of self-reinforcing lower rates of inflation.

30 Indiana Workforce Development Recommendations

https://www.indystar.com/story/money/2022/11/18/indiana-governor-workforce-cabinet-recommends-new-programs/69657309007/

The IndyStar reported on the final recommendations of the “Governor’s Taskforce” earlier this month. I didn’t see much response locally. I believe this is a HUGE opportunity to cooperatively invest in Indiana’s future, by both parties. Indiana’s governor and two houses have been governed by a single party for many years. The historical low-tax, low-service, selective investment strategy has delivered low taxes, responsible local government services, respectable education, solid infrastructure, a diversified economy but mostly growth in just the Indy metro area and lower average incomes for the other 80 counties. The current very low unemployment rates are further squeezing employers reliant upon abundant relatively low wage/skills employees.

Focus. 30 Items are Too Many.

Eliminate One-third of the Lowest Value Initiatives.

  1. Digital development grants. Employers will invest in high ROI projects by themselves.

2. Indiana Talent Agency. No extra bureaucracy.

3. Career Network. No extra bureaucracy. Finding jobs on-line is easy today.

6. College retention incentives. Colleges already have incentives.

10. Immigration reform. Yes, but Indiana will not drive this nationally.

11. Miscellaneous student grants. These would help, but not critically.

12. Transportation funding. Helpful, but not critical.

21. High school diploma flexibility. Critical thinking skills or true CTE skills are essential, Don’t dilute them further.

23. Incentivize CTE credentials. Not needed. If credentials were clearly defined and understood, students and workers would pursue them out of self-interest.

24. STEM curriculum, courses, etc. Focus on schools and teachers first.

29. Scholarship for dual credit completers. These highly talented and motivated students are already moving in the right direction.

Digital Skills (1)

No need for #4 bureaucracy. Basic digital skills should be completed in junior high school. Is the state requirement clear? Advanced digital skills courses should be required in HS and community college for graduation. Make existing courses available for free to firms for remedial on-site training. Make relevant Western Governor’s University courses free. Digital skills should be like “breathing” for Indiana residents. No extra state overhead is required.

University STEM Degrees (2)

No incentives to universities required (5). Provide STEM degree completers with a $25K graduation cash rebate. IU/Purdue (7) should offer more diverse STEM degrees, but so should all Indiana publicly funded universities. Let the students drive the faculty levels.

Career and Technical Education Certifications (3)

Fine-tune the certification program to really recognize workplace, digital, team, industry and technical skills. If the program was recognized like a CPA, licensed plumber, six sigma blackbelt, PMP project manager, Microsoft IT skills, state licensed professional, etc., it would have great value, increasing employee pay and transferable value. (8, 9, 22, 30).

Early Childhood Education (4)

Fund pre-K and K for all. Fix the detailed regulatory limits (13). Defining pre-K detailed results is not essential (26).

Community College (5)

Clearly define “advanced manufacturing” curriculum and degree (1). Reduce community college tuition fees further with state subsidies to encourage universal participation in higher education (like Tennessee). Radically change community college to be local county (or county groups) funded and managed educational institution. Ivy Tech has failed repeatedly as a state-run organization to graduate students. Let local counties decide if they want to invest in education and actively manage this.

Reading (6)

Invest whatever it takes to ensure that all 3rd graders can read at grade level. This is the most essential gateway (28).

Administrative Improvements/Investments (7)

15. Offer employers a $1K fee per class to offer on-site classes.

16. Simplify criminal expungement.

17. Auto enroll eligible students in 21st C scholars.

18. Require HS seniors to file FAFSA.

19. Increase college funding grants for lower income students.

20. Increase credit for prior learning.

28. Fund Dolly Parton library to encourage reading.

High School STEM Classes (8)

25. Allow any person with a BS degree to teach any STEM class at HS and community college level. No need for more detailed subject matter or education course qualifications. They will “figure it out”.

Background on Indiana’s Historical Progress

https://tomkapostasy.com/2021/06/10/is-indiana-better-off/

Summary

Indiana is not winning the modern global competition for value added jobs and firms. Students and adults must have modern skills. Educational institutions must provide these skills. This requires focused investments and administrative changes.

2022 US Election Participation Rates: Fair

Record High Voting Rates in 2018 and 2022

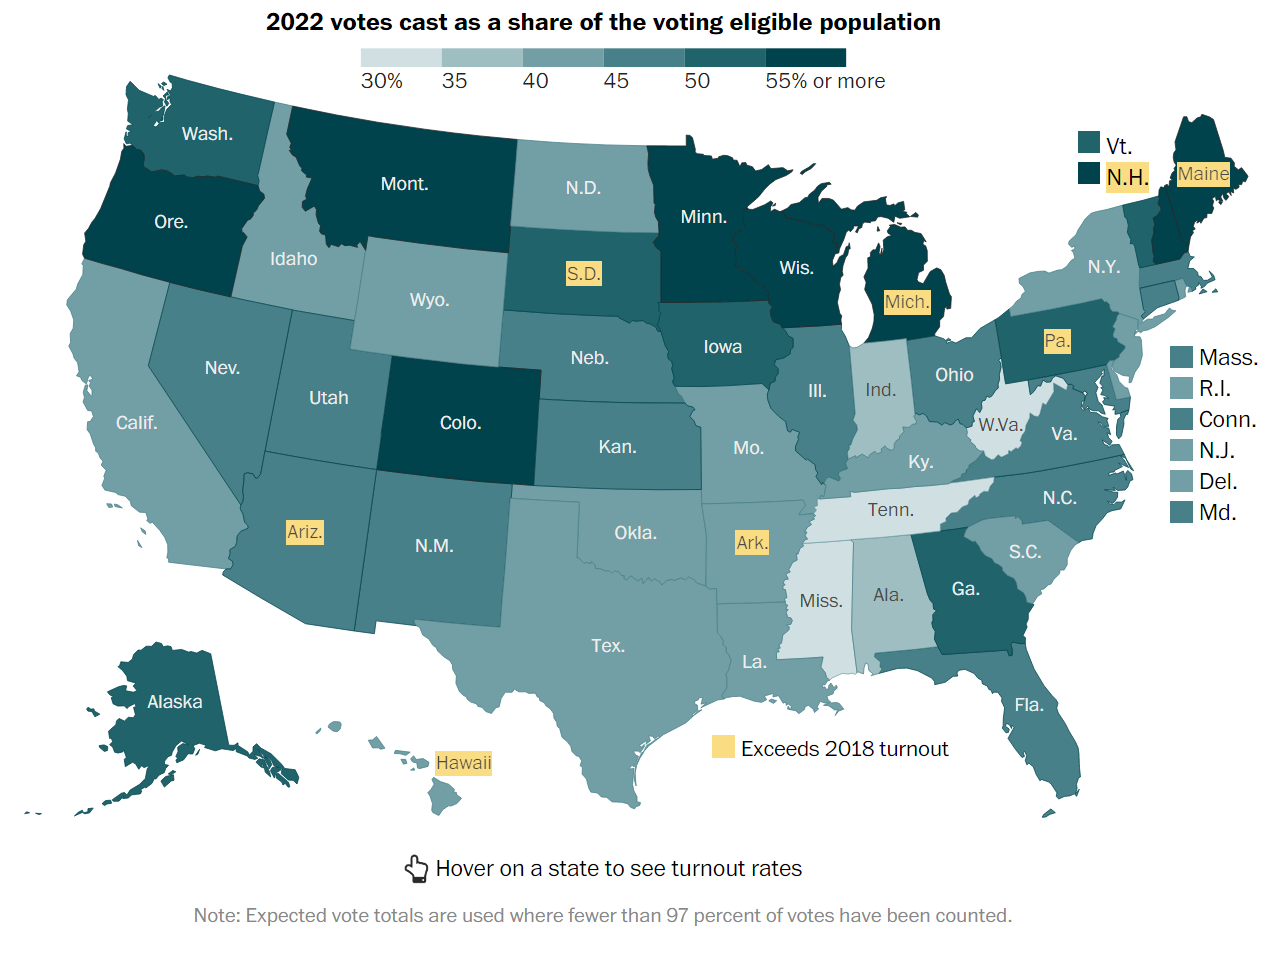
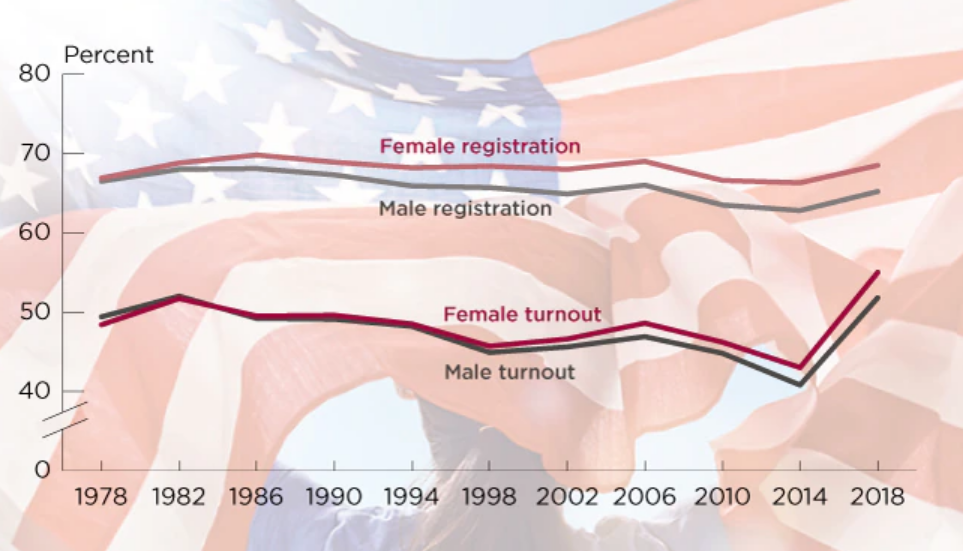
2018 and 2022 elections showed widespread increased voter participation. Increases were seen by all races, genders, income, ages, states and education levels. Increased voting by the youngest age group and Hispanic Americans were most notable.

2022 Voting Higher than Recent Decades, but Lower than Record 2018 and 2022

https://www.washingtonpost.com/politics/interactive/2022/voter-turnout-2022-by-state/

Complete detailed breakdowns are not yet available.
https://www.washingtonpost.com/politics/interactive/2022/voter-turnout-2022-by-state/

Only 8 of 50 states had increased voter participation versus 2018.

https://www.statista.com/statistics/1184621/presidential-election-voter-turnout-rate-state/

https://circle.tufts.edu/latest-research/millions-youth-cast-ballots-decide-key-2022-races

https://circle.tufts.edu/latest-research/half-youth-voted-2020-11-point-increase-2016

Young-adult voting remained above history, but less than the record 2018 performance.

Alternative/Early Voting Remains High

https://www.usnews.com/news/articles/2022-11-04/early-vote-totals-point-toward-record-breaking-turnout-for-midterm-elections

https://www.axios.com/2022/10/22/2022-midterms-early-voter-turnout-numbers-2018

https://www.cnn.com/2022/10/20/politics/voter-turnout-analysis

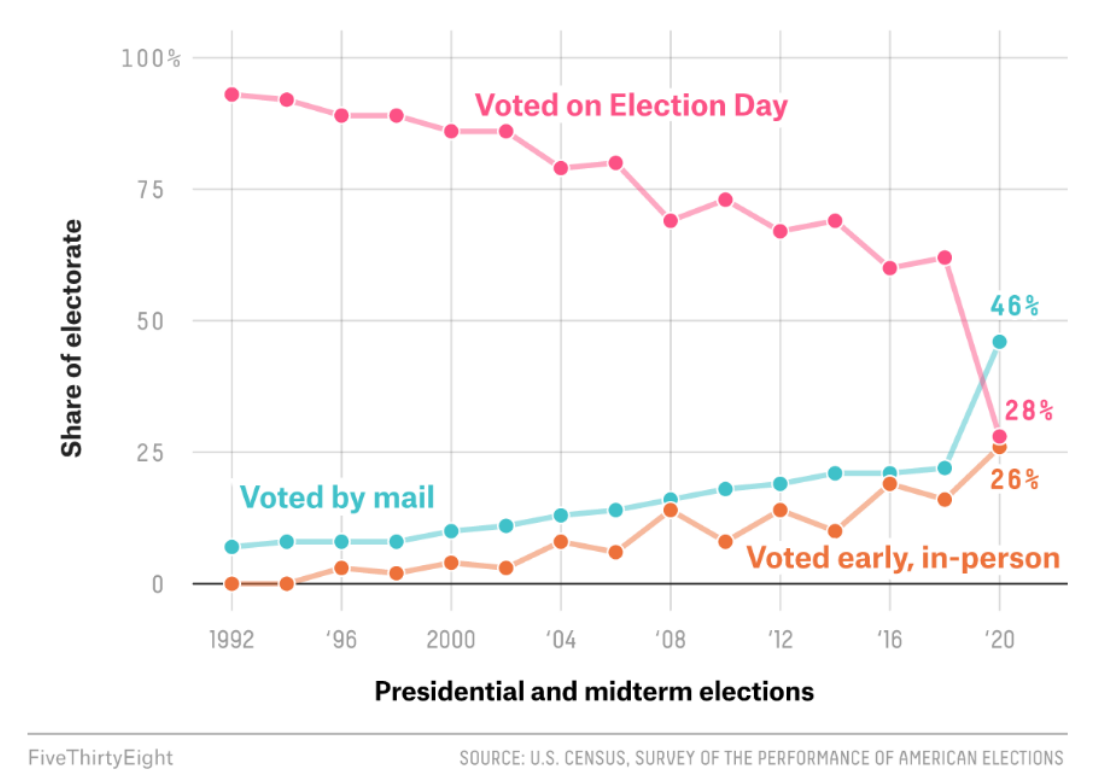
The 2020 and 2022 elections both relied heavily upon mail-in and early voting options. Early voting participation, especially in competitive states, was equal to or ahead of 2018. Hence, election day participation in 2022 was somewhat lower than in the record year.
Voter Registration is as Important as Participation

https://www.census.gov/library/visualizations/2020/comm/participation-congress-election.html

Voter registration in the states with party-preference records increased from 108 million in 2017 to 117 million in 2021 and then a little to 120 million in 2022. Registrations have increased a little faster than voting age population, but have not made a material difference.

https://ballotpedia.org/Partisan_affiliations_of_registered_voters

The Democratic party share has declined significantly in the last 2 decades, replaced by “independent” voters. The Republican party share has declined by just 3%.

Voting Rules Encourage and Discourage Voting

https://www.bbc.com/news/60309566

https://graphics.reuters.com/USA-ELECTION/VOTING-RESTRICTIONS/znvnbdjbkvl/index.html

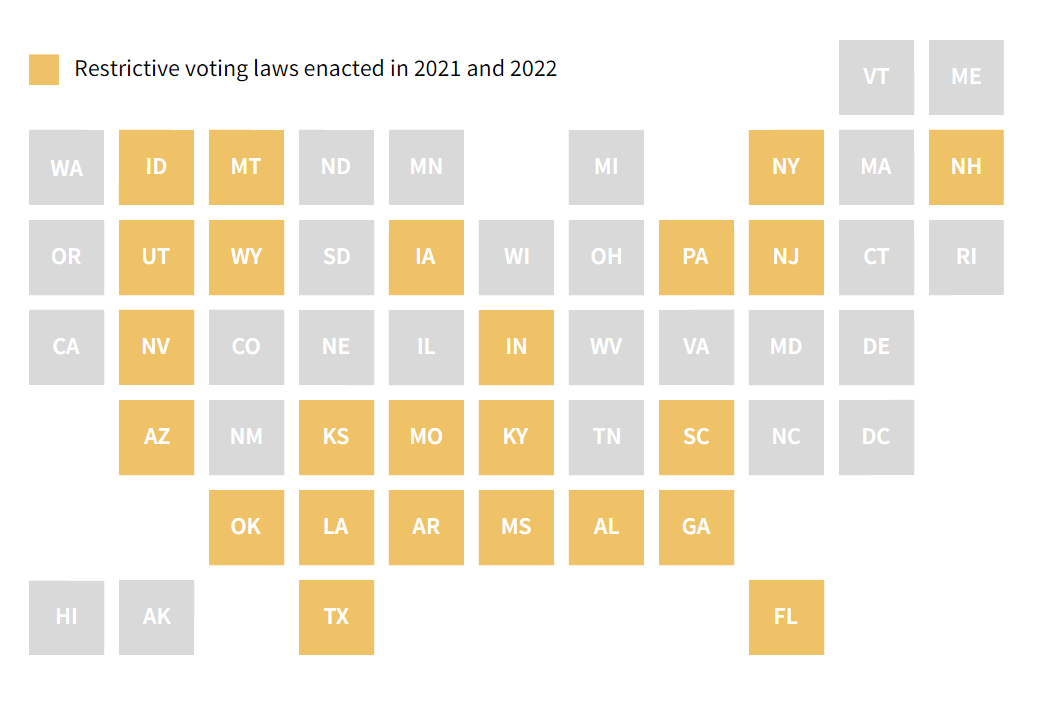
Good data on the impact of various voting law changes is not yet available. Anecdotal media reporting of the 2022 election did not indicate extremely large changes in voter behavior.

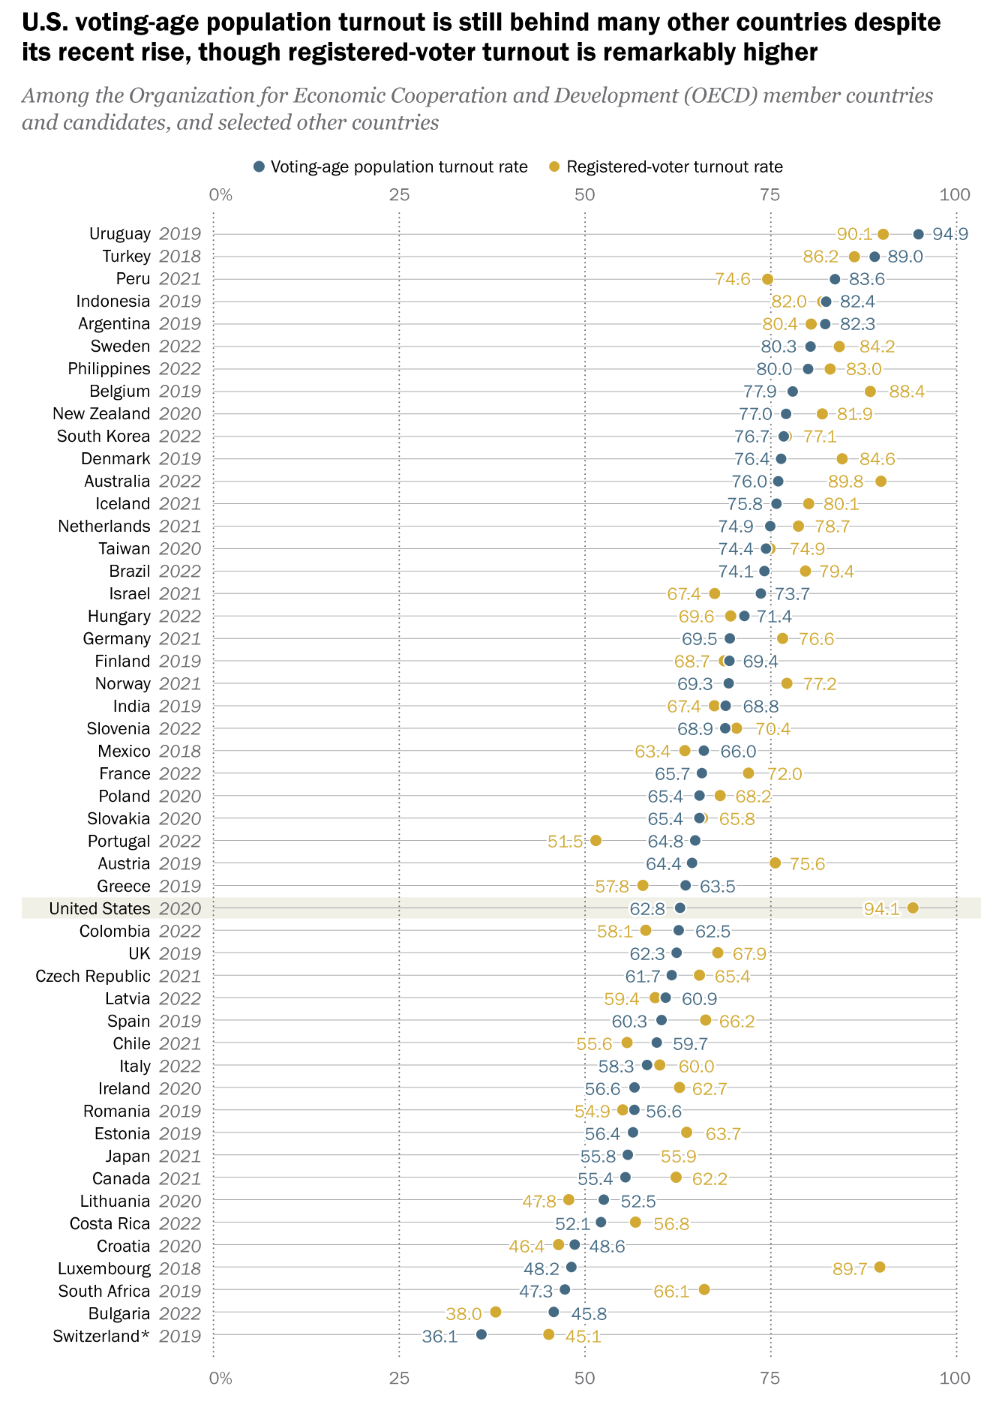
US Registration and Net Participation is Low versus other Advanced Economies

Summary

Voting participation in the US varies significantly by gender, race, age, state, income and education level. It recovered to some degree in 2018-22 following a 40-year low period. Voter registration has increased by a small amount in the last 10 years, but increased participation among registered voters has been the driver of overall results. The availability of mail-in and expanded early voting clearly boosted turn-out in 2020 and 2022. The impact of additional voting restrictions is unclear, but obviously intended to reduce turnout. Polarized politics in the US has increasing voter turnout, but only by 10-15% versus recent history. Presidential years boost turnout by 15%. State by state participation in election years ranges from 58% to 76% (excluding a few extremes), based on habits, demography and state laws. Presidential elections could have 10% higher participation if all states followed the examples of the high participation states.

Government has an increased impact on all citizens. Democracy requires participation to make the decisions and programs of governments (at all levels) legitimate. The US can do better.

Recession!?, Recession!?, I Can’t Find Any Recession!

October State Level Unemployment

https://www.bls.gov/web/laus/laumstrk.htm

15 of the 50 states have unemployment rates in the TWO’s!

The Great Plains region has 7 states with 2% unemployment rates: MN, SD, ND, Mo, KS, NE and IA.

Utah (2.1%) and Idaho (2.9%) standout in the Rocky Mountain states.

In the Southeast, Alabama (2.6%), Florida (2.7%) and Georgia (2.9%) enjoy minimal unemployment.

New Hampshire (2.4%) and Vermont (2.3%) represent New England and Virginia leads the Middle Atlantic (2.7%).

Another 20 states report 3% unemployment rates, for a total of 35 (70%) at 2-3%.

The remaining 15 states and the District of Columbia (4.8%) enjoy 4% unemployment, historically considered better than “full employment”. Illinois (4.6%) and Nevada (4.6%) have the highest unemployment.

September Metro Area Unemployment Rates

https://www.bls.gov/web/metro/laummtrk.htm

A plurality (40%, 149) of the 370 US metropolitan areas report employment rates of 3%, consistent with the 3.5% overall national rate.

More than one-third (34%, 124), enjoy rates in the 2% range!

About one in seven (14%, 51) reflect better than classic “full employment” rates in the 4% range.

24 metro areas (6%) enjoy astonishingly low 1% unemployment rates.

22 metro areas (6%) are outside of “full employment” at 4.9%. 17 are in the 5% range. 5 exhibit 6%+ unemployment rates.

The statistics for just the top 100 metro areas show the same pattern. The distribution of unemployment rates weighted by population shows less dispersion, with just 3% each in the 1% and 5%+ ranges and a heavier 47% in the central 3% range.

22/370 Metro Areas Not at Full Employment (5-7% Unemployment Rates)

California: Yuba City, Madera, Fresno, Hanford, Merced, Bakersfield, Visalia

Texas: Corpus Christi, Brownsville, Beaumont, McAllen

Illinois: Danville, Kankakee, Decatur, Rockford

Michigan: Muskegon, Saginaw, Flint

Pueblo, CO, Rocky Mount, NC, Farmington, NM and Las Vegas, NV

42 of the 50 states enjoy having all of their metro areas with full employment.

24 Metro Areas with Far Better than Full Employment (1% Unemployment Rates)

Missouri: Columbia, Jefferson City, Springfield, St Joseph, Joplin, Cape Girardeau

Lincoln, NE and Ames, IA

Minnesota: Mankato, Rochester, St Cloud, Minneapolis-St Paul

Dakotas: Fargo, Grand Forks, Bismark, Sioux Falls, Rapid City

Utah: Provo, Logan, Ogden, Salt Lake City

Burlington, VT, Columbus, IN and Bloomington, IN

Summary

The labor market stands out as a very positive measure of the health of the US economy in October, 2022. A general, prolonged, material decline in economic health is difficult to see on top of this broadly very positive economic base. A slow-down? Highly likely.

Has Inflation “Turned the Corner”?

http://news.bbc.co.uk/cbbcnews/hi/find_out/guides/trends/rollercoasters/newsid_1578000/1578955.stm

The stock market reacted quite positively yesterday to the slightly better than expected news regarding measured inflation. The total measure and the “core inflation” measure excluding more volatile food and energy prices were both a little lower than expected for the month and for the 12-month calculation.

https://www.cnbc.com/2022/11/09/stock-market-futures-open-to-close-news.html

I don’t think that trend inflation was ever as high as the markets and voters perceived (double digits) and I don’t think that today’s reaction/perception of a peak or recovery in the inflation rate is correct, as inflation totals and details have been slowing for seven months, since March. In hindsight, the business cycle tends to reflect a smooth “sine-wave” curve of increasing, flattening and then decreasing various measures. It is VERY difficult to separate the “signal from the noise” as the monthly data is released on GDP, employment, inflation, etc.

As usual, we need to look at nearly a dozen measures of inflation and its components and 2-3 views of each component to try to identify the “signal”.

When I look at the consumer price index, I see an inflection point in March, 2022, when a quickly accelerating curve paused its growth rate. Inflation appeared to resume at its prior pace in April and May, not faster than in prior months, indicating that March was a fluke, but at about the same pace, indicating that, overall, there was the beginning of a slow-down in Feb-May. In June, I see a second inflection point, and the pace of price growth has clearly slowed for the next 4 months. The annual inflation rate from March to October was 6.2%

The inflation rate from September, 2021 to March, 2022 was 9.8%. This was the highest rate indicated by this data. 6.2% is a good one-third lower than 9.8%, strongly indicating that the inflation rate has peaked. It might not be declining, but it has clearly peaked.

The annual, 12-month price change measure tells the same story. At September, 2021, the trailing annual inflation rate was 5.4%. At March, 2022, the rate had reached 8.6%. It appears to have peaked at that time, levelling off in the low 8% range. A peak was reached in June at 9%. The next 5 months have shown a declining trend to less than 8%.

The monthly percentage change is much more volatile. Monthly changes reached 0.88% in Jun 21 and 1.32% in Jun 22. There were also lower monthly changes during this period, keeping the 12-month measure to 9% or less. The last 4 months have shown good news, with monthly inflation of 0%, 0.1%, 0.4% and 0.4%, a total of 0.9% for 4 months, or 2.7% annually. This measure is too volatile to claim victory, but it reinforces the notion that inflation has peaked and is beginning to decline significantly.

The “core” inflation index appears to have peaked at 6.4% of annual inflation in Feb, 2022. Most economists focus on this measure because the excluded food and energy components are much more volatile and tend to return to their low long-term inflation rates, so high monthly increases tend to be followed by offsetting declines. The core inflation index appears to have levelled off at 6.5%, but evidence of a future decline is not obvious in this measure.

The monthly core inflation measure fluctuates between 0.4% and 0.6% for the last 18 months, indicating annual inflation of 5-7%. A lasting decline is not obvious, but the October measure is encouraging.

The food consumer price index clearly accelerated from late 2020 through mid 2022. Monthly inflation grew from 0.2% in late 2020 to 0.6% in the last 2 quarters of 2021. Food inflation reached 1% monthly in February, 2022 and stayed at that level for 6 months, before beginning to decline quite sharply to 0.6% in the next 4 months.

https://fred.stlouisfed.org/series/CPIUFDSL#0

On a year-over-year basis, it took a little longer for food price inflation to become noticeable, as the earlier lower inflation months were combined with the growing inflation months. In June, 2021, the trailing 12-month food inflation rate was just 2.4%, comparable to the last 30 years. The annual inflation rate reached 6% by November, 2021 and peaked at 11.4% in August, 2022. The monthly food inflation rate and the trailing 12-month rate are clearly declining. Consumers face a grocery bill each week and are sensitive to these changes for key items.

https://fred.stlouisfed.org/series/CPIENGSL#0

Energy prices are volatile. That’s why they’re excluded from the “core” inflation measure. Nonetheless, from a consumer experience and future inflation expectations perspective, they matter. They matter greatly. The gas and electric bills arrive each month. Automobile fuel is purchased weekly or more often with huge price signs at the station. Monthly energy prices increased by 5% in June, 2021 alone and averaged about 2.5% per month for the next year and one-half. Energy prices then briefly increased by 19% in the next 4 months combined before finally dropping a bit. The monthly experience was one of 2 years of increases and 30% annual inflation for more than a year. The recent price reduction is seen as a release from relentless large increases.

https://fred.stlouisfed.org/series/GASREGCOVW

The most visible energy price. for regular auto fuel, dropped from $2.50 per gallon to just $2.00 per gallon during the first year of the pandemic before increasing to $3.00 per gallon in the second year and then up to nearly $5.00 per gallon in June, 2022. It has since declined to a slightly elevated $3.60 per gallon. Consumer perception of “gas prices” is mixed. It’s clearly higher than in 2019, 2020 or 2021, but it has come down from the peak level. Various threats and weekly volatility make consumers shy to conclude that gas prices are “really” declining.

https://fred.stlouisfed.org/series/CPIHOSSL#0

Housing/shelter is the largest component of the CPI. Both rental and home ownership costs are estimated, with adjustments used to try to smooth out variable month-to-month changes.

Annual housing inflation remained in the 2-3% range for the first year of the pandemic, but very quickly climbed to 6-8% as the supply of new homes was reduced and demand for housing of all kinds increased. Consumers saw this inflation in record high rent and housing prices (new or used).

https://fred.stlouisfed.org/series/MSPUS

https://www.cbsnews.com/news/apartment-rent-price-august-dip-realtor-costar/

With the Fed driving higher mortgage interest rates, consumers can afford less housing, so demand for new and used housing has dropped, causing owned and rental prices to flatten or fall.

Consumers have clearly seen the substantial increases in housing values and rents, and the subsequent flattening in recent months. Most consumers would estimate experienced annual housing inflation at more than 10% for the last 2 years and be unsure as to expected future housing and rent prices. When in doubt, consumers are likely to expect the worst; some level of continued increases in rents and total costs (mortgage payments).

https://fred.stlouisfed.org/series/CUSR0000SAD#0

The pandemic’s large consumer and business subsidies lead to a 20% spike in demand for durable consumer goods, which drove a 25% price increase in 18 months. Consumers obviously experienced this large price increase, even though it was implemented over more than a year. Prices effectively peaked by February, 2022 and then returned to their usual 0-2% annual level. Consumers can feel that “everything costs more”. Many durable goods are purchased infrequently, so the new zero inflation will take some time to shape consumer perceptions, but we are already 9 months into this cycle, so consumers are mostly feeling better about this category.

https://fred.stlouisfed.org/series/CPITRNSL

The “transportation” subset of the CPI looks like the durable goods graph. It contains the prices of cars and trucks, the cost of fuel, insurance and maintenance. I think that most consumers would say that transportation costs are up and have not yet begun to fall, even though the index indicates that they plateaued beginning in March, 2022. This is another category where expectations should slowly change to match the numbers.

https://fred.stlouisfed.org/series/CUSR0000SETA02

Used car and truck prices stayed flat or declined in the 7 years before the pandemic. In the 17 months from June, 2020 to November, 2021 they increased by 45% as private vehicle demand increased and new car supplies shrunk. Used car prices have essentially flattened in the last year. Consumers are aware that prices have stopped increasing but suspect car dealers of still trying to raise prices further. A little more positive experience on this higher profile measure will help to reduce inflation expectations.

https://fred.stlouisfed.org/series/CPIMEDSL#0

Medical cost inflation was a bit elevated at 5% heading into the pandemic, then fell to less than 2% during 2021. It has since returned to 5%. Consumers have relatively weak perceptions of medical costs due to the buffer of insurance policies. Most service prices were restrained during the first 2 years of the pandemic as demand for durable goods was up, but demand for services was down.

https://fred.stlouisfed.org/series/LES1252881600Q

Another way that consumers gauge inflation is through their “real”, inflation-adjusted incomes. Real incomes were increasing slowly in the 3 years before the pandemic, following many flat years. Businesses bid up wages during the first year of the pandemic, but then reduced the increases in their offered wages to less than the increase in inflation. Hence, real wages have decreased by about 2% annually in each of the last 2 years. Hence, at a total level, workers are feeling inflation, because their wages are able to buy a little less at the end of 2022 than at the end of 2020 or 2021.

Summary

The data clearly indicates that inflation has peaked and is heading downward. The rate of decline is unclear. It’s unclear how long it will take to return to a stable 0-2% rate. Consumer perceptions are likely to lag the data by 3-6 months.

Total inflation reached an inflection point in June, 2022, pointing to 3% inflation, rather than 8-9%. Core inflation increased quickly throughout 2021 to a 6% annual level, but has remained flat at 6%. Food inflation reached a 12% annual level, but has slowed to 7%. Energy inflation reached 30% for an extended period of time, but has decreased to “just” 20% with high variability. Official housing costs rose by 8% annually, while consumers experienced 10% plus cost increases. The official housing inflation rate has declined a little to 6%, while consumer perceptions of current and future housing inflation are mixed. Durable goods inflation exceeded 12% annually, but has dropped back to its typical 0-2% range. Broadly defined transportation costs increased by 12%+ for more than a year and have flattened out recently at close to zero percent. Medical cost inflation was low after the pandemic, but has increased back up to 5%. Real worker wages have declined by 4% in the last two years, making inflation a felt reality. There is no sign of a wage-price spiral.

The worst of the post-pandemic inflation appears to be over. Key sectors show flat or declining inflation. Gas prices and used car prices are down. Consumers have used up most of their excess savings. Government spending is way down in real terms. Increased interest rates and a tight labor market are slowing the economy. Consumer inflation expectations are coming down with experienced inflation. Barring another major supply chain disruption, inflation should be under 3% before the end of 2023.

A Very Robust Long-term US Labor Market (1970-2021)

A Dozen False Claims of Journalists, Analysts and Pundits

Job growth is too slow, there are not enough jobs.

All of the good jobs are gone, there are fewer good jobs.

The only growth has been in “low wage”, service jobs.

There are no “blue collar” jobs, no “hands-on” work is available today.

Jobs are all “dumbed down”, no real content remains.

Automation, computers and artificial intelligence are eliminating all jobs.

There is no room for advancement at work.

The economy is inherently stagnant, firms are unable to create new positions.

We’ve become a nation of shopkeepers.

There’s no hope for millennials in the job market, Boomers are leaving a disaster.

More and more jobs are subject to the “imposter syndrome”, they really do nothing.

This time is different, we have reached the “end times” for jobs.

The Data Says …

The US Census Bureau and the US Bureau of Labor Statistics attempt to measure the detailed occupations in the evolving US labor market. I have selected 1970 as a baseline because it is effectively prior to the “computer revolution” and within my lifetime of observing the labor market. The US economy was still essentially in the post WWII boom period with manufacturing clearly the most important industry in 1970. Prior to Japanese or Chinese competition. Prior to the “energy crisis” and environmental concerns. Prior to improved social, political and economic opportunities for women, racial and other minorities.

We had 153 million people working in the US labor market in 2021.

https://www.bls.gov/cps/cpsaat11.htm

We had 75-77-79 million people working in 1970.

https://www.census.gov/content/dam/Census/library/publications/1984/demo/pc80-s1-15.pdf

The total measures and the detailed measures are somewhat inconsistent between 1970 and 2021. But, they are adequate to make basic comparisons. The labor force doubled in 50 years. 75 million new jobs created! 15 million new jobs each decade. 1.5 million new jobs each year, on average.

The detailed occupation categories have also changed. The 500+ categories in 1970 are very different from 2021, but the basic measures are roughly consistent. I have mapped the 1970 categories onto the 2021 categories. In 1970, the “undefined” responses were in the 10% range and not reallocated back to the detailed occupations as is done currently. Self-employed individuals were measured differently. Managers and supervisors were measured differently. The current definitions are better aligned with the current jobs. The 1970 categories provided much more detail on the manufacturing sector.

Employment by Job Level

Total employment more than doubled.

The highest level “manager/supervisor” jobs category nearly tripled. 18 million manager/supervisor jobs were added between 1970 and 2021. In 1970, there were 10 million manager/supervisor jobs; 13%, or one out of every 8 positions. The newly added positions are 24% of the labor force in 1970. The 28 million current manager/supervisor roles are 37% of the total 1970 work force. Opportunity, indeed. In 2021 terms, manager/supervisor roles are 18% of the work force, more than one of every six positions.

Professional jobs (college degree plus required) also tripled, growing from 14 to 41 million, an increase of 27 million new jobs. This increase is 36% of the 1970 work force. The manager, supervisor, professional subtotal is 23 million in 1970 (31% of the total). It has grown to 69 million (3X) in 2021, reaching 45% of the labor force. The number of “premium” jobs tripled, while the share of “premium” jobs increased by almost 50% in this half-century. Good news, indeed.

“Skilled” labor jobs were flat across 50 years, declining as a share of total jobs by one-half, from 10% to 5% of the economy. However, their neighbor, technical jobs, increased faster than the economy, adding 10 million high quality positions. The combined skilled labor (trades) and technician/technical level positions increased from 15 to 25 million, overall. This two-thirds growth is slower than the overall labor market’s doubling. Hence, this job level decreased from 20% to 16%, or from one in five to one in six positions. This is a “glass half-full or half-empty” situation. The 14% of the total labor market growth for premium positions is offset by a 4% decline in middle skilled positions, resulting in a 10% increase of combined middle and premium positions as a percentage of the total.

Lower skill level jobs accounted for nearly half of all jobs in 1970; 37 of 75 million. They comprised a decreased 39% of the total in 2021, 59 million out of 153 million. A smaller share of “lower skill” jobs seems like progress. Yet, even here, we have a growing labor market, with 59 million jobs in 2021 versus just 37 million jobs in 1970; 50% more.

The “physical labor” category grew from 22 to 32 million jobs, but it declined from 30% to 21% of the work force. Relatively fewer jobs, absolutely more. The clerical workforce encountered a similar, but less extreme change, growing from 11 to 15 million jobs, but declining from 14% to 10% of the work force. The “service sector” grew twice as fast as the overall economy, increasing from 4 to 12 million jobs and from 6% to 8% of all jobs. The “service sector” is growing disproportionately, but it is a relatively small part of the overall economy, just 8% of the total in 2021.

In total, the lower skilled clerical, labor and service groups combined, grew from 37 million to 59 million positions, but declined from 49% to 39% of all jobs. I see this as progress and look forward to the next half century reducing this category to just 30% of all US jobs.

At the detailed level, we have 70 occupations driving 62 million new jobs, 82% of the 1970 base. We also have 27 occupations experiencing a 12 million jobs loss, 15% of the 1970 base. Joseph Schumpeter’s “creative destruction” model of a dynamic economy is validated. Changes in demand and technology eliminated 12 million jobs, 15% of the total, across 50 years. The US economy is capable of permanently destroying and replacing a quarter million positions each year, about one-fifth to one-third of one percent of total employment.

Let’s go back to the dozen negative claims. Is there support in the details? Are there “good” jobs being destroyed? I only see declines due to “natural causes”: improved IT, telecom, process/quality/manufacturing, international trade, railroad, textile automation/imports, ag productivity, printing and DIY office options.

On the upside, what do we see? Management and supervisor roles growing in all areas in a more complex environment with higher sales volume, more products, faster product introduction, more exports, more outsourcing of functions, greater customer demands in all dimensions, global sourcing and competition.

Technology supplemented/infused positions at all levels. Cashiers, customer service reps, distribution employees, tellers and drivers today leverage IT systems and processes.

Increased specialization/technical skill in many service/technical areas. Retail terminals. WMS. HRIS. EDI. Customer service scripts. Web based transactions.

Increased professional skills, sophistication and impact in all areas.

More professional teachers, nurses, analysts, accountants, lawyers, HR, real estate and financial advisors.

Diverse technical computer, automation, lab, design, legal, teaching, culinary and design technical positions.

More medical, food service and personal care service roles.

Summary

In the last 50 years the US labor market has doubled in size and added an increasing share of managerial/professional/technical positions.

In my next blog, I’ll focus on the next level of detail: 17 categories of the US labor market.